Showing posts with label Treasury. Show all posts

Thursday, July 12, 2012

COMPLETE COLLAPSE OF TRUST


Retail investors have shunned the equity markets as they feel as though they are rigged.  I talk to people all the time that don't care what kind of interest rate they receive, they just don't want to lose money.  In the last month we've been handed a couple of new scandals that reinforce that the entire financial system is similar to visiting a crooked casino with fixed tables and slot machines.

THE HITS JUST KEEP ON COMING
Think back for a moment and recall these assaults on market participants;

2007-2011 - Large bank mortgage fraud and financial crisis resulting in bail outs
2008 - Bernie Madoff ponzi
2009 - R Allen Standford (Standford Financial Group) ponzi
2011 - 2012 - Banks caught manipulating Libor rates during the crisis
2011 - MF Global collapse where segregated account monies are stolen
2012 - JPM is involved in a total meltdown of its "hedge position" related to corporate bond interest rates.  Initially the loss is estimated at $2B, now it could be as high as $5B.
2012 - Peregrine Financial and PFG Best implosion where $220 Million is missing

And who can forget this one?

THE GREATEST CON OF ALL
2008 - 2012 - Federal Reserve ravages the American public and crushes pensioners and savers in an attempt to boost housing thereby saving banks.

We will soon find I am sure that the Fed was completely aware of the manipulation of Libor and rather than do anything about it, was happy to let this go because the business of the Fed is really the business of the biggest banks.  

10 YEAR TREASURIES SIGNAL EVERYTHING IS JUST FINE?
Let's take a look at the Fed's handiwork.  Below is a graph of the 10 Year Treasury Yield which now shows we are sub 1.50% at 1.48%!   - Source Bloomberg


I hope you didn't bet against treasuries thinking that because we were at historical lows, we couldn't go lower!  We are now within a few basis points of all-time lows.  Certainly this is a picture of financial health, right?

5 Yr View - 10 Yr Yield - http://online.wsj.com/mdc/public/page/mdc_bonds.html


The killer here is that this action by the Fed via "Operation Twist" and the inaction or complete incompetence of the SEC, CFTC, NFA, and FED to regulate banks, brokerages, futures trading firms, and themselves is that drives regular investors away from markets that may actually provide some return into assets that are completely worthless or in term of inflation, money losers.

Investors scrambling to get out of equities have chased yield into corporate bonds.  The Merrill Lynch US Corporate Bond Index with 1 to 10 year maturities is pegged at a 2.76% yield!  So, if these investors don't already have these bond holdings and are looking to buy today, they are weighing taking on a 5 to 7 year bond with some company risk, and perhaps even some interest rate risk, and lots of inflation risk for some taxable yield that is less than 3%!  Are you kidding me?

WHY NOT MUNIS?
I mentioned taxes, so how about one of those safe municipal bonds?    Muni's are even scarier.  We are now seeing a host of cities threaten or actually file for bankruptcy as they are finally coming to grips with the reality that they can't pay 100% of the healthcare cost of employees and retirees and also can't promise an 8% return for life on their pensions.  Meredith Whitney may be finally redeemed although her timing has been off, but that is how it is when you are making dire predictions in a completely manipulated environment.  As an investor, I have felt that individual municipal bonds are frankly difficult to invest in simply because it is too hard to do prudent financial analysis on the city in real time.  Often, the city's financials are released with significant delays and therefore an investor must rely on those awesome rating agencies who always are ahead of the game in determining financial risk!

In addition to the perils associated with knowing what you are buying, the yield on municipals are lows as well, adding to the danger and the poor risk and reward pay off.  Merrill Lynch's 7 to 12 year muni index suggest that the average yield is a staggering 1.76%!  So much for retiring, Mom and Pop.

DIVIDEND PAYING STOCKS RIGHT?
For almost two years I've been advocating the approach to buy dividend paying multi-national firms as an approach to investing.  First, I suggested this because it was an attempt to pre-invest ahead of portfolio managers as they realized after us that we were heading for recession.  Second, I felt like government stimulus would help these larger firms.

Can we continue to invest in this area?  Maybe, the real issue is that there may not be a place to hide if the economy continues to slow.  Yes, these stocks will fall less, even if you are in utilities and healthcare because everything could go down, the play here would be to try to minimize those losses as much as possible.  Perhaps buyers of those treasuries are right after all, in this new normal, perhaps 1.48% for 10 year risk on a government that is deficit spending like no other country has ever done is a great deal!


GOATMUG

Goatmug is an investor that cares about you and your family. Goatmug's Blog - Financial Perspectives From The Mountain Top is a collection of thoughts on our economy and how it impacts the lives of investors and average people. While several specific investments are named in many of his posts, these articles are simply invitations for you to do your own research and reference to these securities does not constitute financial advice. Your situation is complex and unique and you should seek professional assistance with your trading and investing. Please visit Goatmug and share your comments athttp://www.goatmug.blogspot.com/


Thursday, September 22, 2011

CLOSED FOREVER - (UNMET EXPECTATIONS MEET REALITY)

We were hungry and cold and we absolutely needed a warm meal.  Yesterday was special, we had reservations at our favorite eatery called the FOMC Diner.  Everyone had been so excited about our afternoon meal and the anticipation had simply been unbearable.  As we parked and walked across the street we were startled to see a sign that rocked us to the core, we were speechless, and worst of all we had the realization that our hope for free desserts to go along with our stimulating meal would be unmet.  Somehow, the FOMC Diner had closed its doors......forever.


OUR DINER OWNER, BEN TELLS US HE IS OUT OF BUSINESS
The much anticipated Federal Reserve meeting decision was made yesterday and within an hour the market finally acknowledged what we've stated for almost two years; that the Fed is out of bullets.  After two and a half years of getting pounded by a false market fueled by hope and trust that unlimited printed money could fix the world debt and solvency crisis, we have been been conditioned to expect the impossible from Ben Bernanke and his friends, but alas we have finally seen that he is a hollow man, simply a shell with little or no substance.

Rather than assault the Chairman with paragraph after paragraph of text describing how he has misled investors and damaged the average senior citizen in favor of banks and the financial elite I will simply highlight the implications of this moment where the world awakened to the impotency of the Fed.  The significant troubles we face are global and cannot be solved with easy fixes or more electronic dollars.  Financial pain is going to be delivered, the question is, who will suffer and how much.

A TWIST OF THE KNIFE
When the Fed released their statement and plan yesterday they essentially told us that they would begin selling treasuries that were short dated (2 to 5 years) and they would buy in the market about $120 Billion in treasuries that were long dated (20+ years).  (The total program is $400 Billion) The impact of this action will actually be that the yield curve should rise on the front end and longer term rates should fall.  The Fed tells us that they are doing this in hopes of stimulating the mortgage market and reviving the housing sector.  I don't buy that and in fact, I strongly believe that this action (the purchase of long dated bonds) was to meet the funding needs of the US Treasury to ensure that we can sell treasuries to someone.  The Fed is essentially budgeting these purchases.  Thus, the Fed and Treasury's coordination helps to fund the government and also put a cap on interest expenses for US debt.  So much for an independent Fed right?!  The situation could get much worse for the Treasury as well since effectively the US government has already spent all of the funds from the last budget battle and is in need of another tranche of money.  I haven't discerned any new love and cooperation between the two political parties over the last couple of months and therefore anticipate that we could actually have a government shut down and perhaps more rating agency downgrades. 

US BANK DESTRUCTION
Banks have been suffering in the last couple of weeks and that fall has accelerated over the last few days.  Since banks borrow "short" and then lend "long", the impact of Operation Twist is that banks will need to pay more for their money and then they will receive less if they actually lend it out to borrowers because longer dated rates should begin to fall.  This movement in rates is making the yield curve flatter, this is exactly what banks hate as they make lots of money when the curve is steep.  In the last several years we have seen the Fed act in the markets with the goal of sustaining and supporting banks and financial institutions no matter how badly it would impact the overall economy or the US financial position.  The key metric that makes the Fed unable to preform more QE is simply that these actions have been strongly correlated to price increases in food, energy, and other commodities (and gold).  Essentially the Fed's hands are tied and Operation Twist was more about meeting government needs for interest rate control and funding than helping anyone else out.  Actually if you think about the implications here, this action further damages retirees and pension funds as their investments are further crushed since most are using long dated bonds for a large portion of their portfolios and they benefit from higher longer term interest rates.

US RECESSION
Many of the metrics I report monthly have shown that our economy has been slowing down and has probably already been in recession for months.  If you felt strongly that this wasn't the case, you might as well throw in the towel as the last vestige of hope was destroyed as asset prices have fallen and we'll see a failure of confidence drive the final nail in the coffin for the economy.  If the Fed is right (and they are always right) then asset prices are the key to recovery AND asset prices are the key to misery and deflation.  Since the maneuvers of the last two years of Fed intervention have produced no tangible lasting economic results then we must assume that the collapse of prices since May 1st will seal the deal and confirm that the US is or will be contracting significantly with no turnaround in sight.  In otherwords, the asset collapse will kill the remains of the business confidence and therefore kill the potential growth that might be in the works.

GREEK DEFAULT AND EURO CHANGE ON TAP
Remember that little area of the world that we would forget every other week when the ECB proclaims that everything is fixed or when the Fed would come out and promise they would do something next month?  Oh yes, that little area.  Unfortunately, Europe is still there and they still have their little issue called Greece.  The Fed whiff yesterday coupled with the complete mess of the Eurozone has heightened the problems and perhaps made the dire straights the world is in more clear.  While the Fed has made USD swaps available to the ECB and foreign banks, the entire area is beginning to fall apart.  The Greeks need another slug of money to stay afloat for a few months and they have been forced to promise that they are really really serious about austerity this time!  Unfortunately for them, the Germans are getting tired of these never-ending bail outs and are realizing that they are going to be on the hook for a larger and larger share of inevitible losses.  Senior German officials are dropping out of the ECB, IMF, and Eurozone leadership and this could signal that they are making subtle moves to extract themselves from this nasty financial disaster called the Euro. 

In recent developments we have seen the contaigen of sovereign insolvency get a bit more serious as several major corporations have removed their excess Euro reserves from French banks and moved them directly to the ECB.  As stewards of these reserves can you blame the corporate executives of these firms?  No, of course not, however this "bank run" demonstrates just how fragile these banks are and how capital impaired they will be in the event of a Greek exit (default).

As I suggested the other day, the ECB and IMF continue to pressure Greece into tougher and deeper cuts which have a circular and negative effect on their economy.  As Greek leaders lay off government workers they harm the economy and as the economy is hurt as more businesses close and exit the nation.  As businesses fail, tax revenues decrease, and more cuts are required.  At some point, Greece will wake up and realize that it is better to pull the scab off at one horrible moment (default and exit the Euro) and reemerge with its own currency rather than destory everything and sell (give away) all of its assets to lenders over years.  I give this 6 to 9 months more at most before Greeks take these actions.

SO NOW WHAT?  TRADING UPDATE
I wrote yesterday that the markets were in no man's land and that investors should wait for clarity before taking a short or long position.  With one more day behind us we've witnessed a -283 point drop on the DJIA and also today's beating of -391 points to end the session at 10,733.  At the cross below 11,250 we essentially got the green light to short with abandon and today's bloodbath was a confirmation of that.  I would not be shocked to see some rallying as the sellers take a breather, so personally, I will add some shorts as we rally higher.

SHOW ME THE MONEY!
Why do I have this kind of conviction despite the 750 point drop in markets?  The reason is simple, show me where the catalyst is for buying?  We have an impotent Fed, we have a disintegrating Euro, we have a slowing economy, we have a broken political system that argues over additional spending when  we should be cutting, and we have US banks that are about to blow up again (see BAC).  I'll be clear, we will probably get a pop here as we bounce off the 200 week moving average in my Weekly 4 Yr Chart, but I will be using that as an opportunity to bet on a further decline.  My hope would be that we rally up to the 11,000 area, I'm just not sure we'll get there.   

$DJI -
Overhead Resistance - 11,000
A convincing break down through 10,700 will mean we will add to shorts with target of 9,750.


If you are absolutely committed to being long the market you must look to the relative value trades we have been highlighting for several months.  Those are the utilities, healthcare, consumer staples, and defense stocks.  (XLU, XLV, XLP, and PPA).  Even these conservative plays could be troublesome in this environment because healthcare and defense should be on the chopping block for reductions in government spending.  Portfolio managers will be looking to buy dividend producing stocks like McDonald's, Coke, and others and hide out in these safer areas.  They will simply look to outperform the overall index and proclaim that they "beat" the market.  Personally I don't like that approach, but there are folks that feel like they must be in, and if that is you, this is where the safer water will be.

ALL of those charts are resting on support.  If we have another rough and negative day, all of those positions are sells in my opinion.

If the downward trend continues for another few weeks we will see a coalacing of politicians that begin to find common ground to make headway and restore confidence.  There will be calls to the Federal Reserve to provide stability and leadership in the wayward markets.  At that moment we will see a final coordinated effort from central banks around the world to step in and halt the financial destruction with loan and debt guarantees and never-ending liquidity.  Ultimately these efforts will fail, but it may provide the last boost before everything simply falls apart.  This could be the point at which gold blows through $2,000 as confidence in the existing global monetary system is utterly destroyed once and for all.

WEEKEND EMERGENCY MEETING
You need to know there is a meeting of the IMF this weekend in Washington D.C. and we could see some emergence of a plan, however I don't think this will be the "Stimulus That Ends All Stimulus" quite yet.  The US markets need to endure a bit more pain to achieve the mobilization of the Treasury, Fed, the White House, and both sides of the aisle.  When they are all acting in tandem, then we will see the last attempt at shoring up the collapsing ponzi scheme.  Till then, this weekend may provide a small bit of fuel to give sellers higher prices to unload.  Europeans are hurting and as an example the EWI (the Italian ETF) is down 50% since May, if the USA was in the same neighborhood, I would guarantee action.

Let me sum this all up for you.  The economy in the US is getting worse.  The economies in the emerging markets are slowing down, the economies in Europe are a disaster, the banks in Europe are about to implode, US banks are under attack and Bank of America may use the nuclear option on its Countrywide purchase, and now the facade of a powerful and helpful Fed has been destroyed.  If we are lucky markets will stay range bound and simply idle along, but at this point I anticipate troubling stories about Greece and Europe's banks to continue to drive markets much lower.  Be careful!

GOATMUG


Goatmug is an investor that cares about you and your family. Goatmug's Blog - Financial Perspectives From The Mountain Top is a collection of thoughts on our economy and how it impacts the lives of investors and average people. While several specific investments are named in many of his posts, these articles are simply invitations for you to do your own research and reference to these securities does not constitute financial advice. Your situation is complex and unique and you should seek professional assistance with your trading and investing. Please visit Goatmug and share your comments at http://www.goatmug.blogspot.com/

Sunday, August 7, 2011

IT'S NOW A CON....CONFIDENCE GAME

We don't have time for long posts and rants about the stupidity of politicians, the Fed, ECB, and US Treasury so I'll be very quick about where we're at and what I expect.

WHAT WAS WITH THE DROP LAST WEEK
Last's week drop was about Europe (Italy and Spain) and how the leadership of the European Central Bank, IMF, and leading countries are fractured and have no solution to the debt problems in the Eurozone.  Trouble has moved from the PIIGS to the inner circle and the bond market has called BS on the entire Euro structure.  Because the leadership in these organizations came  out with three different versions of solutions and all of them were half-baked and incoherent the equity markets got blasted globally.

RATINGS DOWNGRADE A NOTHING BURGER?
Yes, the ratings downgrade was about 3 years overdue.  Yes the Tea Party forced the issue.  Yes the Democrats and RINOS agreed to much more, but the agreement was a sham just like the final agreement.  None of that mattered, the ratings agencies should have downgraded the US a long time ago and Standard and Poors was sending a much needed message to the politicians that they need to get our situation handled fast.  Democrats will say we need taxes, Republicans will say we need tax cuts.  I will say we need a flat corporate tax at about 20% that will unemploy hundreds and thousands of accountants that game the system and we need to start with GE.  We can also tax folks a bit more if they make more than $1.5 million a year and raise that rate to 40%.  We need to cut SS benefits, Medicare, and cut all foreign aid by 75%.  We need to have 10% cuts in every department in the Federal government to start.  We need to put Congress on a 401K and put them on a normal health plan and finally set two term limit maximums for Senators and three term limits for Congress.

WHAT WILL HAPPEN NEXT WEEK
The real answer is, "I don't know".  From the perspective of the European leadership,what needs to happen is that the ECB, IMF, and entire Eurozone with backing of the FED need to come out with a strong statement saying that they have a plan to buy up all the sovereign debt on the market and they are a backstop and will not let bond yields go above some number.  Yes, this takes huge firepower in terms of money but its all digital money anyway isn't it?  I'm writing this in a tongue in cheek fashion, but IF they want to have some market stability the only thing that can help is coming out swinging with a limitless plan that is overwhelming.  If the markets detect any weakness or fragmentation then all bets are off and those evil "bond vigilantes" will come back with a vengeance.  Let me be clear, this is not a real solution, nor is it viable for a sustained recovery, but these guys are just trying to keep the system alive.  The real answer is bond investors taking haircuts and losing billions of dollars, but so far the leadership in each area of the world has tried to prevent this needed solution from happening. 

This may only buy them a few weeks or months, but this is what must happen to prevent a total meltdown tomorrow. 

If the financial leaders come up with a solution as I suggest, we could actually see markets trade MUCH higher over the coming days.  If there is no solution or the sharks smell the blood of a divided Eurozone with no German backing, a market rout is sure to play out. 

Overseas markets in the Middle East traded down significantly this weekend.  Futures just opened up and the Dow Futures are down 270 as I'm typing, but there is lots of time left for the IMF, ECB, the Fed, US Treasury, and the President to do their overnight magic and work markets higher. 

MONEY MARKETS ARE STILL A HUGE CONCERN
I have received a couple of emails this weekend about where investors can hide in this mess.  The trouble is that most average investors don't have good places to "hide" because the money market funds they would normally go to could be much riskier than some of the non-money market options.  If you can short, then short and be careful, but I'm writing the following information with Joe-6 Pack investor in mind.

With that warning made, you could consider some short term investment grade corporate bonds as an alternative to money markets.  This strategy is not without risk, BUT there are positives here in the sense that investors will shun stocks for treasuries and corporate bonds if things get really nasty (nastier).  Companies have a lot of cash on their balance sheets and sometimes you'd rather risk the event risk associated with one company over taking a gamble on what time bomb is held in a money market that you have no control over.

I hate to say it but you need to stick with the ideas I posted several days ago in the midst of the total rout of the market, because if indeed this ship is righted you will need a "relative value play" for some of your money.  Please read GOLD IS GOOD, SOME COMMODITIES, THEN THE REST.

The thrust of that post is simply this.
1)  The Un-Currency (Gold) is probably best especially in the event that the ECB subverts national power and usurps the individual nation state's power and begins to issue Eurozone bonds.  Couple that with a QEIII being unleashed in some form and it is a place to not only hide but to gain.  Physical holdings are better.

2)  Selective commodity plays may also be winners however the entire global growth story is crashing to an end, so therefore you must only buy commodities that may be in short supply like agricultural commodities.  Oil will be subject in the short run to a fall.

3)  Dividend paying equities will also be relative winners.  Remember long only funds must go somewhere so by choosing these positions you may also lose, but the bet here is to lose less than the broader market.  I don't like this strategy, but some folks just feel like they need to be in the market 100% at all times (and remember those money markets can be and are risky too!).  These dividend paying stocks also compensate you while holding them.  Think firms like Phillip Morris (MO) and Campbell's Soup (CPB).

4)  I also outlined a longer term strategy of owning dividend paying commodity producing stocks.  Now this is going to be very volatile in the short run, but from a longer term perspective I think this is one of those long term home runs since they own everything that will go up in value as the dollar continues to crater.

I still haven't gotten a total body count on the damage that last week did to hedge funds.  Last week's volatility and commodity destruction surely blew up a few trading firms. 

GOATMUG

Goatmug is an investor that cares about you and your family. Goatmug's Blog - Financial Perspectives From The Mountain Top is a collection of thoughts on our economy and how it impacts the lives of investors and average people. While several specific investments are named in many of his posts, these articles are simply invitations for you to do your own research and reference to these securities does not constitute financial advice. Your situation is complex and unique and you should seek professional assistance with your trading and investing. Please visit Goatmug and share your comments at http://www.goatmug.blogspot.com

Monday, July 4, 2011

WE BELIEVE IN A STRONG DOLLAR POLICY....

GEITHNER TRIES HIS HAND AT COMEDY
It is time to review the month end US Dollar Index values for June. Each time I examine these figures I am reminded that Timothy Geithner said in May 2009 that he "backs a strong dollar and that Chinese assets are very safe". Recall as well that the Chinese students in attendance laughed. (Reuters)


Below is our US Dollar Index value chart which captures monthly closing prices. I use this chart to see if Timmy was serious about backing that "Strong Dollar".


TRANSITORY DOLLAR INFLATION

Hmmmm, while there have been a few surges, there really isn't much of a direction change here at all.  Perhaps those Chinese students were quite discerning and couldn't hide their disbelief when being lied to. On May 29th, 2009 the US Dollar Index closed at $79.43. As of June 30th 2011 we are now at $74.47. I guess our belief in a strong dollar policy was only "transitory" as well. Perhaps the Treasury Secretary may go pro as a comedian once the debt ceiling negotiation farce has been completed.


GOATMUG

Goatmug is an investor that cares about you and your family. Goatmug's Blog - Financial Perspectives From The Mountain Top is a collection of thoughts on our economy and how it impacts the lives of investors and average people. While several specific investments are named in many of his posts, these articles are simply invitations for you to do your own research and reference to these securities does not constitute financial advice. Your situation is complex and unique and you should seek professional assistance with your trading and investing. Please visit Goatmug and share your comments at http://www.goatmug.blogspot.com/

Wednesday, June 1, 2011

WHY TELL THE TRUTH WHEN YOU CAN LIE? (US TREASURY & THE FED)

SAME STORY, SAME LIES
If you read economic news long enough you will start to see the same tired story spun the same way over and over and over again with little variation.  This is especially true when listening to the President, CONgress, the Fed, and the US Treasury.  It is not surprising to see this because people (leadership) tend to give the people what they want to hear rather than what they need to hear.

Think about it.  We have an government that is spending in an out of control fashion like a shopaholic, we have a deficit that is greater than $1 Trillion more than we take in, we have hit the demarcation point where Social Security and Medicare are spending more than they take in, we have a Federal Reserve that is buying our own debt keeping rates so low older people can't earn enough, we have exceeded our self-imposed government debt limit, and we have a banking system that is really insolvent.  Have you heard any of this stuff really discussed in an open forum or seen the leadership come forward and propose a real plan that is thoughtfully considered? 

The answer is no.  Even President Obama has completely ignored every single recommendation that his own budget deficit reduction panel provided.

TWO GOOD ONES THAT EVERYONE LOVES TO HEAR
So, it is odd to see someone other than fellow bloggers generate a post or article that states something other than the normal bilge of conventional wisdom or sound bites.  Today, I found one piece that actually stuck out, because it flies directly in the face of what we hear from Treasury Secretary Timothy Geithner.  In fact, recall that every single time Tim Geithner speaks he states several lies over and over again.  Here they are;

1)  The USA believes in a strong dollar policy!  HAHAHA!  Remember when he said this in Beijing and the Chinese business students simply laughed out loud in his face?  That was one of the funniest common lies.  We Americans are either too polite or too stupid to do anything but nod our heads when he says this to us. 


(Totally unrelated video, but really funny considering these are the folks that are laughing at our Treasury Secretary!  Oh and by the way, don't click the video when it gets going, I have no idea where it will take you)
2)  Mr. Geithner also is fond of telling us that China is bad and that their currency is undervalued.  In other words, we are looking for a scape goat to complain about our trade deficit and this one has been an easy one to throw out there, because Americans are all about "Good Guys" and "Bad Guys".  (Don't get me wrong, those Communist Chinese are bad guys, but that is not the point of this post).  When Geithner says, "Chinese are bad", we all pile on and clap and howl and scream, and CONgress does the same thing too.

WHO LET THESE GUYS WRITE THIS STUFF?
Given that Geithner loves to throw these two out, I found it remarkable that the St. Louis Fed wrote a one page note stating that in fact, that perhaps it wouldn't be a great thing if China did actually revalue their currency higher.  They mentioned that the yuan had actually increased in value by almost 25% since 2005 and yet it did nothing to stall the increasing trade deficit with the most populous nation in the world.    Further, if we did have a Chinese currency that was valued higher, WE IN THE USA would have a HIGHER INFLATION RATE!  In other words, things would be much more expensive if the garbage we buy from China cost more (via an appreciated and more expensive yuan). 

http://research.stlouisfed.org/publications/mt/20110601/cover.pdf?utm_source=Twitter&utm_medium=SM&utm_campaign=Twitter

(Go ahead and read it, it's 1 page!- make sure that you right-click and open in a new window though!)

Yes, that is the take away, while we've simply swallowed the trash that our leaders provide to us, we often never question the extent of their understanding or their ability to actually tell the truth.  The St. Louis Fed says that we'd have more inflation here.  But beyond that, you know what would really happen.  If China appreciated their currency we'd have importers and businesses going to Thailand, Malaysia, Vietnam, and every other 3rd world poverty stricken country looking for cheap labor to replace the suddenly more expensive junk from China.  I guess that then Geithner could complain about those countries and their terrible trade policies and deficits huh?

Ultimately, Mr. Geithner, The US Treasury, The Fed, CONgress, and the President don't want to address the real issues, we want to point fingers at others and sink our heads in the sand.  The St. Louis Fed document is interesting, but certainly is something that won't be repeated in interviews or Sunday morning talk shows.  It is far easier to blame others and refuse to address real issues.

WHO WROTE THIS? - NICE DISCLAIMER!
Oh yes, it didn't escape me that the authors of the paper just happen to have interesting sir names, perhaps these folks went off the reservation or we'll soon find that Chinese spies have even infiltrated the highest ranks of the Federal Reserve system.
(Mingyu Chen and Yi Wen were the authors).
Finally, you have to love the disclaimer at the end - Perhaps I'll start adding that same disclosure to everything that Goatmug writes as well..... so here goes.

"Views expressed do not necessarily reflect official positions of the Federal Reserve System".


GOATMUG

Friday, May 27, 2011

JOE 6 PACK LEARNS FROM BERNANKE AND GOES TO THE POKEY

JUST DOING WHAT OUR LEADERS DO -
While scanning the news I was struck by the irony of this story from the San Francisco CBS affiliate.
Samuel Kioski was arrested recently for an inventive application of Ben Bernanke's magical printing tricks.

http://sanfrancisco.cbslocal.com/2011/05/26/technician-faces-charges-of-cleaning-out-bay-area-atms/

REPLACING WORTHLESS DOLLARS WITH WORTHLESS PAPER
Allegedly, Mr. Kioski was an ATM technician who replaced almost $200,000 of real money for fake copies of dollar bills.  In his "rampage" Samuel opened up a total of 7 machines, grabbed the real cash, and dropped in bad forgeries into the cash dispensers.  The police stated that the fake money was not even a good attempt as he simply made the bills on a copy machine. 

The repairman was able to sneak away since last July with his haul, but was found two weeks ago in Arizona. 

YOU NEED TO BE A BANKER TO GET AWAY WITH THIS
See, Mr. Kioski didn't quite understand that you must have a PHD from Yale or Harvard and also deal in billions rather than hundreds of thousands to get away with this sort of trick.  Our central bankers have pulled off the exact same scheme, but instead of going to jail, they are lauded as heros.  Think back to the scary days of the economic collapse.  When the full impact of the Lehman implosion was being felt, we watched as Goldman Sachs, Bank of America, JP Morgan, and others swapped their toxic assets with us for clean, crisp, and freshly printed digital dollars.  We taxpayers (our leadership and the Fed) were more than happy to trade worthless paper (MBS) for our currency in the name of avoiding disaster. 

Compare the TARP swap with the trade Mr. Kioski made and you'll find little difference between his moves and those of the Fed, Treasury, and the bankers; little difference besides that it was a small amount and not sanctioned by the thieves at the NY Fed. 

WHO IS THE BIGGER CRIMINAL?


RULES TO STEAL BY -
So the takeaway from this story is that if you are going to pull a fast one and take money from folks, you must follow these rules to get away with your booty.

1)    Take money from taxpayers, not banks
2)    Rip folks off for billions or trillions, not thousands
3)    Wear suits and talk about the end of the financial system, everyone will hand over the money immediately
4)    Go to Davos, not somewhere like Arizona
5)    Take your wife with you, then she won't file a missing persons report

GOATMUG


Tuesday, September 7, 2010

MONOPOLY LESSONS FOR A BEAR MARKET - SEPTEMBER UPDATE

SEPTEMBER UPDATE
I need to make this post really quick since I have so much going on.  I will be posting quite a few times over the next week or so because I have a lot of material (economic) that I want to share.  Overall, we are seeing divergent data coming through as usual, so we'll have to wait and see where we fall.  In general, I tend to believe the longer term theme that I've laid out that our economic situation for consumers is slowly grinding to a halt while big business is taking full advantage of the globalization of the world economy and managing to keep busy.  I think this is why some of this data remains stubbornly positive despite what Joe 6 Pack is feeling here in the US.  The fact that large multi-nationals are diverse enough to show gains abroad is great and is really beneficial to the US economy, if we didn't have that, I think we'd be in a much worse position.

TOTAL RAIL TRAFFIC - http://railfax.transmatch.com/
Rail traffic can reversed its season decline and all carriers have resumed their forward march.  They still are 10%-20% less than the 2008 period, but they continue to improve.  I need to find some truck shipping data because I have a feeling that trucking companies are opting to load their trucks on rails to save on transit costs.  This obviously makes rail shipping look better.

Total Rail Traffic

MOTOR VEHICLES (RAIL TONNAGE)
Auto shipments rebounded.  As I mentioned last month, it looked like a seasonal decline was causing a drop.  I'm interested to see what happens here in the next quarter as the green line really ramped higher last year.  Is there pent up demand or will this begin to flat line?


WASTE & SCRAP RAIL TONNAGE
Interesting, it looks as though scrap shipments are coming back in line with the 2008 and 2009 level which leaves me wonder what was happening over the last few quarters to fuel the spike.  I believe we will see the same trend happen with those auto shipments.  Despite the leveling off of scrap shipments, scrap prices do continue higher.  See the chart below for those details.


FOOD STAMPS (SNAP DATA) - http://www.fns.usda.gov/pd/34SNAPmonthly.htm
Generally speaking, there is no change in the trend for government food stamp recipients.  There is an ever increasing number of families on government assistance.  I know things are rough and this is highlighting the divide between the haves and have nots.  A person in the US does not need more tax write offs or rebates or enticements to buy more "green" energy stuff or other overpriced crap, they need jobs.
41.2 million people are taking food stamps which is a total of 19.1 million households.  Benefit costs per year continue to edge up at $5.5 Billion.  The average household is receiving $287.00 a month in assistance. 


MONSTER EMPLOYMENT INDEX - http://about-monster.com/employment-index
We've commented on how the Monster Employment Index had been steadily improving as employers continued to buy advertising slots to fill their positions.  Over the last two months we've seen a decline in the listings as June was the index high at 141.  At the end of August we are at 136.  This is still high end of the range for the last year, but clearly we've seen a softening.


HOUSING
I am purposely omitting a discussion on housing.  I am attempting to obtain approval to use a few charts that I found from a great blogger on the topic.  As soon as he grants permission to copy the charts I'll make a post in the next week.  Chart or no chart, the housing market is terrible.


WLI DATA - http://www.businesscycle.com/resources/
WLI data continues to flounder in the low 120's area.  If you've followed any of the recent debate about the usefulness of their data you'd be completely confused.  The ECRI folks have submitted that their data is not an indicator of a recession, or should I say they are saying that their data does not suggest a double dip, however they have consistently advertised that their data can predict recessions.  I think we are simply seeing that all data is completely fouled up due to government influences in the market.  The Fed and Treasury have flooded the markets with excess liquidity that is doing nothing for the general economy, rather propping up asset values (and doing a poor job of it too).  These liquidity streams are really wreaking havoc with the WLI and also the Bloomberg Financial Conditions Index in my opinion.  While overall data is weak, the components that deal with easy money availability are signaling that the good times are here.  The conflicting information is causing these metrics to fail.


MIT/MOODY'S COMMERCIAL PROPERTY INDEX - http://web.mit.edu/cre/research/credl/tbi.html
MIT and Moody's data shows that all is not so good on a national level for commercial real estate.  Price moves up have been met with corresponding drops.  Overall, stock market prices for commercial real estate (CRE) have been doing wonderful this year, as I'm sure that much of the improvement has been a relief that the complete meltdown that everyone expected has not come.  Yet, these are the exact times when we should be examining these investments that have had their relief rallies and now are left with a dose of reality.  Perhaps it is wise to review shorts of several real estate investments?


COSTAR - http://www.costar.com/about/article.aspx?id=7719
Costar is suggesting exactly the same.  I like this chart because it breaks down the space by type of property.  While there are regional improvements, especially in the Western US, the overall health of the CRE space is poor and declining.


SCRAP METALS COMPOSITE - http://www.scrap.net/cgi-bin/composite_prices.cgi?id=100000&num=5
As we've covered several times, Alan Greenspan used scrap metal as a way to take the economic "temperature" of the economy.  We continue to see prices rise here, but I'll be watching for a breakout above these levels to signal that some real recovery activity might be going on.  All in all this may be a reflection of international demand and dollar weakness.


BALTIC DRY GOODS SHIPPING - http://www.bloomberg.com/apps/quote?ticker=BDIY:IND
Speaking of international demand, we are seeing continued improvement in the BDI.  I'm still bullish on pricing for this index to go higher.  If you are looking at this space as an investment, remember that few shippers are leveraged to this metric as they've contracted out their fleets for longer term deals.  There are a couple of shippers that are tied more to the daily rate and you should do some homework on those names.  The bottom line here is that most shippers are leveraged to an extreme and they are subject to dividend cuts (which is why many people own these types of firms).  So, faced with a cut of dividend and high leverage, I tend to shy away from these firms.  Although one can argue that with pricing as bad as it it now, there is only one way to go and it is up!


1 WEEK LIBOR - http://www.homefinance.nl/
Despite rumors of poor banking lending in Europe and around the world, we continue to see 1 week Libor and all other dates come in.  This would normally be an indicator of health in the system as bankers are "trusting" each other more and therefore demanding less of an interest rate for 1 week exposure.  As mentioned above, government interference in this space causes me to question any rate or improvement I see, especially with the concerns that European banks may need more capital.  While this is USD Libor, we are seeing the same rate reductions in all rate curves.


US FINANCIAL CONDITIONS INDEX - http://www.bloomberg.com/apps/quote?ticker=BFCIUS:IND
The USCI has edged above 0 again which would suggest that we are now in recovery mode and in an expansion! HA!  As mentioned with WLI, I have to question it.  The big move is a result of the rebound in the stock market over the last week.  As we have covered, this is exactly the strategy of the Fed, if asset values move higher, people believe that the recovery is in.  Once they believe the recovery is in, they spend like crazy adding to their debt and spending beyond their means for instant gratification!  I'm not buying it and Mom and Pop are not buying it either.  We'll continue to watch this one.


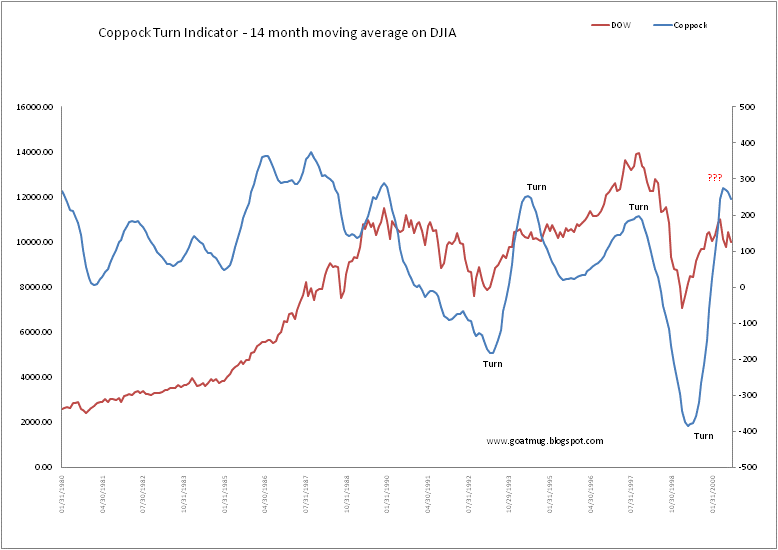
COPPOCK TURN INDICATOR
Since I posted the Coppock turn signal in June there has been no looking back.  The signal continues to suggest that you should be out of the market rather than in.  The thing has a decent track record, but won't get you in early  on the turns because it is based on a 14 month average, however, on big swings it does give you decent signals.


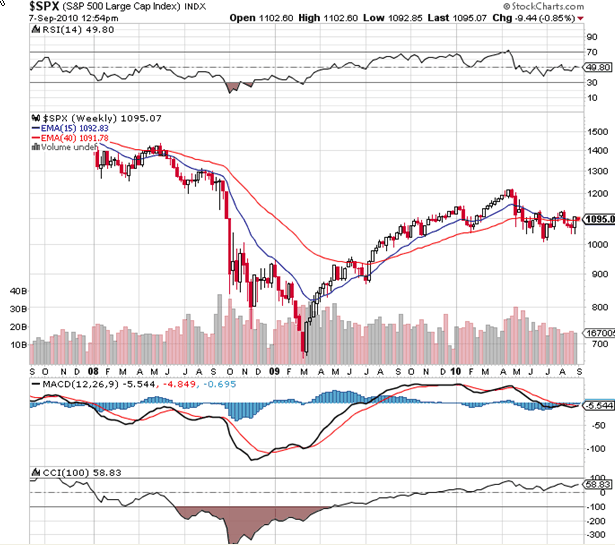
S&P 500 15 DAY / 40 DAY EMA CROSSOVER
Last week's rally has put another bearish chart into question.  We'll need to watch this set up as I type this today, the signal will go back to bearish.  As many know, one of my favorite bloggers Chris Puplava suggests that a very long term signal for market declines is the 15/40 Crossover on a weekly chart confirmed with a sub-50 RSI.  As I posted several weeks ago, we did get that signal in the S&P500.  I wanted to post this here because you might get the sense that I'm bearish (and that would be correct), but I want to make sure that I'm not caught leaning one way when it really is a false signal.  Of real importance is that the DOW has NOT crossed over and therefore is not confirming the action in the S&P500.


USD -http://www.bloomberg.com/apps/quote?ticker=DXY:IND
The US dollar has almost lost all of its gains made in that last several months.  How easy it was for Fed President Bullard and Chairman Bernake to slash the value of the dollar!


TREASURIES (TLT)
Treasuries continue to remain above the levels that suggest stress in the financial system.  While TLT trades higher we must acknowledge that much of the gap higher is related to the Fed's QE program where they buy treasuries.  Of course this incited a stampede to get in front of the FED so we have traded down a bit once the rush abated.  I have spoken with several people that want to short treasuries or buy TBT but I would caution against this trade unless it is very short term in nature.  What we all need to understand is that this program is here for the long haul and we'll continue to see record setting low rates across the spectrum of the debt curve.  We will see 3.25% or 3.5% 30 year mortgages and to have that come to fruition, we'll need to see TLT go higher.


TRADING UPDATE
As bearish as things are beginning to look, I am very concerned when it seems like the entire universe shares my pessimistic view.  I was noting that last week and guess what, we got a big rally!  Fortunately I continued to stay long in the emerging markets strategy I've advocated since July and have rebounded nicely.  In fact, holdings in Singapore and Malaysia continue to outperform.  As we enter September I am going to scale out of positions, or if I retain them, will marry them to a short position to have downside coverage.  I still like corporate debt, but so does everyone else, so I haven't added any bonds to my portfolio in a long time and don't anticipate adding unless I see something come out that is being unloaded by a distressed seller.

For longer term trades, I still believe 100% in my anti-US strategy of going long emerging markets and gold.  The Fed has put us on notice that they will monetize debt and drive the value of the dollar down in an attempt to stimulate, stimulate, stimulate! 

I had an interesting conversation with a few professional oil and gas traders last week.  They reflected that this has been one of the toughest trading years that they can recall.  They were very concerned that top notch guys were getting blown up with the wild swings from day to day.  They commented that several big firms were really in bad shape.  It is these types of conversations that continue to keep me out of oil and gas because you can be directionally correct, but have someone blow up and move the entire market against you. 

MONOPOLY AND THE BEAR MARKET OF 2010
This is dangerous work and it pays to be cautious, patient, and above all protect your capital. I played an online version of Monopoly with my kids the other day and we had an unusual experience that is an example of what will happen in real life in the coming years.


In our online game a computer player landed on an unowned space and he decided that he did not want to buy the property. In our example, when the buyer doesn't want the property, it is sent to auction where all of the other players can bid on it. (Perhaps the real game is like this too, but I never remembered that). In our game we really wanted this Boardwalk-like property and had lots of cash to purchase it since we'd had terrible luck with our rolls. All of the other players were really strapped for cash since they had bought other properties due to their good rolls. Since I'm teaching them "economics and game theory" we entered a clever bid in hopes of stealing this prime property on the cheap. What happened next was very unusual. As the time to enter bids expired we received a notice on the screen that we were the only bidder for the property and therefore bought it for almost nothing!
The message is simple and clear. In Monopoly and in real life bear markets, there will be opportunities, you need to have cash to be able to take advantage of them. Patience is a trade so protect your capital!


Be careful!
GOATMUG


Thursday, August 26, 2010

GOOOOOOD MORNING GDP!

Just wanted to make a quick post reminding everyone that tomorrow morning we'll have a release by the government stating the second quarter's revised GDP report. As you can tell by how the market has been trading, there are now lowered expectations for growth. In the last month expectations have dropped from 2.5% to now somewhere around 1.4%. So needless to say, the market has a lot of emphasis put on this one information release.


A print of greater than expectations would probably goose the market higher right at the open while a print in the low 1.0% area will all but deliver a final body blow to those that have been suggesting that we are not going to double dip. Don't you recall back in April when you were hearing people say that there was no chance of a double dip? I sure do, I got a few emails stating that I was always emphasizing negative data and we weren't going to have another peek at recession.

As I mentioned to them, they were probably correct, but only because it was evident that we didn't ever come out of one.

Anyway, since the expectations in the market have been so managed and the tone in the market is pretty negative it may pay to at least think through the contrarian view. I almost expect to see any large gap down met with buying if the number is nasty (1% ish..).  If the number comes in above the managed expectations, we may see a jump, but I think we'll sell off after the fact as people will realize that the market is bouncing because it is happy about a less bad horrible scenario.  The only thing that holds me back here from getting long if we have some upward momentum is that we did close under 10,000 again, we still have really negative technicals, we are entering the September and October period which is usually more horrible than other months. In addition, we closed very poorly as folks crowed out to get out of the way of the GDP report. This clearly wasn't an end today with positive conviction.

Finally, if GDP announcements weren't enough, the Fed's round table meeting in Jackon Hole, Wyoming will wrap up and if the GDP number is very negative, expect our Fed Chairman to come out with unusual and extraordinary doses of financial shock and awe! I'm guessing that he'll admit things are slowing and suggest that the Fed has lots of ammunition to deal with the decline in growth. Of course all the measures won't really be effective and will not really produce any meaningful improvement long term. The issues are still cemented in place and we won't see any REAL improvement until they are attacked. Just so we have a handy list, here they are;
1) People don't have jobs
2) Because people don't have jobs and they've been without one for a long period, they are losing their homes to foreclosure...
3) Because people don't have jobs, they can't buy these foreclosure homes left by their neighbors.
4) If people have a job and still have a decent credit score, they might be able to refinance, but if they do refinance, they are using that to pay down debt, not spend more. (The Fed has wanted more spending not paying down debt).
5) Having said that, most people with jobs don't have a decent credit score, and therefore cannot refinance their mortgage.
6) Many others not buy houses either because they don't have 10% or 20% to put toward a down payment.
7) Without buyers, housing won't be fixed and banks have begun actually enforcing and processing foreclosures which will add more inventory to the huge backlog of unsold homes.
8) Against this backdrop, Mom and Pop have stopped spending and are now believers in paying down debt and bragging about how little they paid for clothes at Target and Wal-Mart.
9) Businesses cannot sell products to people that don't have jobs, don't have large houses they never really couldn't afford in the first place, and sell fewer products to people that are bragging about how little they spend now.
10) Businesses now face a working environment where they do not have certainty about their future sales, tax, and regulatory environments. In other words, they are pretty sure that their sales are stagnating, taxes are going higher, and they will be forced to pay more for health benefits for their staff and any new people that might be added. Since they have convinced themselves that this is highly likely they are not attempting to add staff (expenses) when their sales are flat to declining.
11) Because business profits are declining, tax revenues for cities, states, and the federal government are horrible.
12) Because cities, states, and the federal government have become accustom to ever increasing taxes they have been devastated for their long term mismanagement of our dollars. They have overspent on useless projects, promised free benefits to everyone, and richly compensated themselves with healthcare and pension plans that are without match in the private sector. These shortfalls of revenues for the second year will add to layoffs of government workers and reductions in benefits (if we tax payers are lucky).

And to fix all of these problems our Administrations, Congress, Treasury Department, and the Federal Reserve have attempted to rescue us by issuing more debt and even gone so far as to buy more of our debt with our own money.

My guess is that Ben Bernanke will tell us tomorrow that he's got it all covered. He'll stimulate the economy, get jobs growing, get banks lending, and do it all through the power of financial engineering and monetary policy. Call it QE (Quantitative Easing), call it debasing the dollar, call it outright purchases of stocks and bonds, no matter what he calls it, it will be an attempt to cover up the core problems and its real impact will be to destroy the value of our currency and further drive us into an oblivion of unpayable debt.


Cross your fingers, tomorrow will be interesting.

GOATMUG

Wednesday, February 24, 2010

WLI Data - 2/12/2010 - 4 WEEKS OF DECLINE

I haven't posted the WLI data in a while, but wanted to post it here now and not wait for the March update. The dip in the blue line shows that the Weekly Leading Indicators index published by ECRI http://www.businesscycle.com/resources/ . The interesting thing is that the data shows a 4 week consecutive drop and I can only expect when they publish the 2/19/10 data it will show the same.

I also track the 4 week average for this data and while it has not turned negative, almost any reading next week will confirm this drop as well.

I've mentioned this data set often as a good indicator that shows if we are coming in or out of a recession, however I've also discussed that much of the data in the leading indicators index can be pushed around by floods of liquidity (as we've experienced in amounts that blow the mind!).


I can only imagine that the WLI and also the FCI will be hampered and show contractions as the Fed attempts to draw down the juice in the system. I've also commented that this won't be possible in the long run as the markets have only been able to fake a recovery because of the extraordinary measures taken by our central bank, US Treasury, and the Administration.

If this trend continues the notion of higher interest rates could certainly be delayed and the double dip I'm suggested my be coming. I don't want to over-react as I still think we've got a month or two left of momentum higher, but the stage is being set for an April / early May top in the market.

Notice as well that the top of this recent WLI move is still at a similar level as the January 2000 level which ushered in the tech blow up. I personally hope that we don't have similar results in the market, but I wouldn't bet against it.

Goatmug

Sunday, January 3, 2010

Outlook from the Moutain Top for 2010

Predictions are interesting because they allow us to really document and work through what we think and feel. We'll revisit these predictions throughout the year to measure how we're doing. No matter how negative I want to be, I still understand that the Fed is spewing its flood of funds at a pace that has not been seen before. The massive liquidity has been the fuel for the ascent back to the 10500 level in the Dow, an amazing almost 4000 point run up in the index. Our government is committed to see assets increase in value no matter the life-style cost in the longer term. Remember, this asset value increase is so important to re-establish confidence in the financial system. If J6P (Joe six-pack) doesn't believe in the integrity of the system a key player has left the table. Much of the moves of the government are meant to get him back in the game.

One last note - don't forget risk. It is really neat to see the huge gains the market posted last year. Don't make the mistake of forgetting that the entire financial system was almost destroyed in the process. The market is still down some 35% from the Oct 2007 highs. Yes, you can go to Vegas and plunk down your entire net worth on red or black and make an easy fortune, the problem is that this is a tremendous risk as well. What significant changes have been made in the market to remove the risk from the system? What would embolden you to take more risk now.

Let me hear from you on the comments section. I'd love to know your perspective.

I will make a new post regarding year-end / month end analysis over the next couple of days to set up trades for the coming month.

2010 PREDICTIONS

ECONOMY

Interest Rates will rise, but not at the direction of the Fed. - The market will demand a more just compensation for the risk it has taken in Treasuries. The 30-year will hit 6%. The market is predicting a rise in the Fed Funds rate coming in August, but I think they will delay raising rates overtly until November or December at the earliest. Any slow down in the economy will be another excuse not to raise them at all in 2010.


While the Fed stated they will stop Quantitative Easing in March of 2010, they will not be able to stop because losses on their book will be immense.


Housing issues will improve through April at which time the impact of increasing interest rates will force the hands of banks and they will begin to release their inventory of "non-foreclosed homes" on the market pushing the new wave of speculators underwater teaching them that falling knives are tough to catch. Some are pointing to the HAMP requirements that state that banks that had home owners that modified mortgages and failed to keep the terms of the deal (make their payments) must release this inventory and use short sales as the tool to divest themselves of the inventory as another reason for a coming drop in home prices. I don't see it that way, I see the government changing their minds again and lifting this requirement when they figure out that it could hurt the recovery.


We will see at least 2 currency devaluations in 2010. These will manifest themselves in the form a North Korea style announcement where you will wake up and the currency will be declared -10% less in value or more. These devaluations are necessary to continue each country's desire to sell goods cheaply abroad. The US' motivation of course is simply to reduce the relative amount of the crushing debt that we continue to heap upon ourselves.


Fannie Mae and Freddie Mac will become the dumping ground for all private mortgages loans made in 2009 and 2010. The banks will avoid taking losses and pass all of them to the US taxpayer. The Christmas present (uh-unlimited losses) that the government gave the US tax-payer on Christmas day is unbelievable. For the next 3 years the loss limits on these two organizations have been lifted and we are backing them with a blank check.


The Euro will face continued pressure, the US dollar will rise significantly against the Euro from the 1.432 level it is as of this writing. The US dollar will actually fall relative to the South Korean won, Australian dollar, and many other commodity based economy currencies. The dollar will strengthen against the yen.


Small business lending and personal credit will continue to decline through 2010.


Gold will actually decline to the $950 area and then move higher later on in the year when it becomes increasingly obvious that Bernanke and Geithner have no intention of pulling liquidity. This will be the opportunity to add more to the position. Gold ends the year in the $1150 to $1200 range. Longer term, gold is still a buy.

US equity markets will end the year slightly positive (meaning less than 5%). This year will be volatile and gains should be harvested when they are acquired. This means that there will be periods of gains and you need to take advantage of the ranges in the markets and buy at the low end and sell at the high end. I still maintain that the Fed will support this market directly or indirectly at all costs. As housing reverses, be prepared to see unexplainable increases in equity markets. Bernanke knows the conventional thoughts that the collapse in 1937 occurred because the Fed increased rates too soon, he'll be sure not to repeat that lesson. This is how we'll be sure to over inflate and also create the next collapse in 2011 or 2012.

FOREIGN POLICY

Middle East tensions will boil over. The US will give Israel the green light to defend herself and presumptively attack Iran. Russia and China will condemn the attack and they will choose the side of their trading partner against Israel by selling arms and providing material support.


Upon attacking Iran, Syria and Lebanon will engage Israel on their northern fronts.


Oil moves to $100 this is based on the continued debasement of our currency through the actions of the Fed and Treasury and also geopolitical tensions.


US POLITICS

Republicans sweep away the majority held by the Democrats in the mid-term elections. The third-party movement continues to garner support but is quashed by the two party system.


Obama names a replacement for Justice Ginsberg who retires in 2010.


Obama is able to pass some sort of health reform. He passes the reform knowing that it is unconstitutional. The strategy is to destroy the health care industry as we know it in the next several years. When the high court determines that the legislation cannot stand, a one-payer system (government) medical system will be the only option left to pick up the pieces. The final step will not take place till 2013 or 2014. No matter what, abortion will be a major component of the bill and will not be removed.


NATIONAL SECURITY / PERSONAL RIGHTS

Despite failed terror attempts our personal rights and privacy will continue to be eroded in the name of our safety. Our government will continue to take measures to protect you after each attempt (meaning safety measures that will waste your time and add little to your safety).


RELIGION
Christians continue to be attacked for their beliefs (read by the secular world as intolerance) and there will be several prosecutions of Christians for their beliefs. This will of course continue in Europe, but will also begin in the United States.

There they are. I reserve the right to add more as I see them, but I'll add them to the bottom and date them so they will be easily identified.

Monday, December 28, 2009

Give Us Something To Believe In

I wrote this article and submitteed it to Tim Knight's Slope of Hope. He usually will post my contributions only on the weekends because they are so long, so I will go ahead and publish it here in case it doesn't fit with his year-end line up. I will post a very quick (I know-I promise it will not be lengthy) updates on where I think the market is from a trading perspective and how to look at the positions we've mentioned in the past. Right now other than the last piece of my KSU that I exited this morning I have no positions.

I've documented the history of actions that caused our crisis and outlined the steps our government has taken to "bail us out". You may find the most recent post at Goatmug's Blog where we discuss The Best Cup of Coffee Ever and how it seemed wonderful and solved all of my problems, yet ended up bitter and disappointing. As I've mentioned, I believe many of the steps taken have either not worked at all, created other problems, or simply hidden the problems. Let's take a few of the items I pointed to in the last post and review the impact and results of their actions

A) The Federal Reserve and Treasury along with other world central banks stepped in and offered their fiscal support and immediately lowered rates again to near zero. Remember, these are front month rates and are the interest rates the government charges banks for overnight money. The Fed voted in recent weeks to keep rates stable at effectively zero percent interest. They voted to do so some 18 months since the beginning of the crisis and 9 months after the beginning of what we now know as one of the largest rebounds in stock market history. In spite of the rally we are still around the 10,500 level on the Dow which is where we traded in January of 2006 and well below the lofty 14,000 area of October of 2007. Am I saying that we cannot return to these areas? No, in fact if the Treasury department remains committed to devaluing the dollar, I can paint a scenario where that might be a real outcome. I doubt it seriously, but it could happen.

Timothy Geithner gave an interview last week on NPR that should put us all on notice. In his words, we will not have a retest or slowdown after this recession. Although many of his other predictions have been flat out wrong, I have a strange sense that he is committed to not letting that happen no matter what. http://www.npr.org/templates/story/story.php?storyId=121778778

Mr. Geithner is only speaking of a short term pull back that he'll help us avoid, for it is too obvious that the Fed and Treasury actions create bubbles and meltdowns and they are coming with increasing speed. I liken this to a drug addict. At first there is pleasure in the use of the substance. Next there is dependency, and then an increasing need for the larger portions of the drug in greater frequency. Think about friends, family members, and others that fit this drug addict description. It usually never has a happy ending does it? I think what we're about to experience is "tough love" provided by our investors. Our friends, (Chinese, British, folks in the Middle East), are about to hold a frightening intervention with the addict and therefore we will be told that we need to shape up and cut out our drug abuse. Unfortunately, I don't think the addict will listen. It is too tempting to let all of that debt go to waste and too hard to cut spending and cut promises and entitlements.

So what are the results of these actions? Interest rates are still low and creating asset bubbles. - Banks and other bank holding companies...er investment banks and insurance companies can now borrow at zero overnight and buy stocks, bonds, and commodities. Is there any wonder why all markets are screaming? What happens when that money is taken back? Remember, this money was intended to buttress balance sheets and also intended to be lent out to companies and consumers, not find their way to the casino!

Banks receive this money and will lend. - NOPE! This has not happened. This I believe is one of the greatest lies that has been made in this crisis. Why would any smart banker lend in the teeth of a nasty, jobless recession? Would you? If you looked at a firm that is asking for credit and he tells you that their business is slowing and they need a loan to make payroll, do you think they are a good risk? Asking bankers to lose money on bad loans is not a solution to the crisis. On a positive note, I am hearing some of my clients being contacted by banks that are desiring to lend on decent terms now. This may be an indication of some thawing.

B) The Fed also bought toxic securities outright from troubled financial institutions and traded those assets for treasuries. Our government offered the TARP funds to help institutions and even made outright purchases of banks and insurance companies. (AIG, Citbank, etc.) We even used these to buy and lend stakes to great car companies like GM! We keep reading that many of the banks and insurance companies that we lent TARP money to have repaid us and we (the US taxpayer) may have actually made some money on these loans. The reality is that we may have made some money on loans that have been repaid, but we have taken a bath on the loans that will never be repaid. Making AIG a government controlled entity makes certain that more losses are headed our way. The Treasury Department and Fed's lack of negotiation with AIG's creditors should be enough to convince anyone that the well connected firms like PIMCO, Goldman Sachs, and Blackrock were feasting on the carcasses of weakened and dying financial firms. In addition, these same favored companies have become the mechanism by which the FED and Treasury actually implement their policies. These companies are providing transaction support (spreads), participating in deals, and also offering consulting services

So what are the results of these actions?
AIG is a mess and still 85% owned by the US. Isn't it great we are in the insurance business?
GM - is still GM.
Goldman, Blackrock, and PIMCO are killing it .

Remember too big to fail? - As a result of the forced marriages between JPM and Washington Mutual, BAC and Merrill Lynch, Wells Fargo and Wachovia, we now have a greater concentration of larger institutions. Seems like the US government has now created larger risk pockets and concentrated more power in less hands. Finally, the repaid TARP money is being used like a slush fund now. The administration and Geithner said they had "extra TARP money" that they could use! Excuse me, just because it is appropriated doesn't mean we need to use it if everything is all fixed, right?
C) In concert with these actions our government also looked to perform direct support (cynics would call it manipulation) in the mortgage market and the treasury market. By guaranteeing and supporting the FHA the US taxpayer became the lender/insurer to 80% of the post-collapse mortgage market. With the announcement of quantitative easing by the Fed we began buying our own treasuries to try to keep prices low and contain rising interest rates.

While short-term manipulation has been successful, it is just that - short term. The bond market is bigger than any one central government and the bet made by Bernanke is going to be called. Once that happens interest rates will climb (and as I type this we are seeing 30 year mortgage rates 10bps higher in one day last week!). THIS IS A HUGE MOVE BY THE WAY! Who will step in to fill the void of the government in this volume at these rates? Stabilizing the home market is job #1 - The government has artificially lowered interest rates and become the dumping ground for all banks to offload their paper on the US taxpayer. Few banks are doing direct lending to residential borrowers without FHA backing. Home sales look to be moving up, but we must ask how long this will continue if rates jump substantially, cash for houses go away, the FED stops buying MBS (stops being the market), or banks actually release the huge backlog of foreclosures that they have kept on their books.

Don't get me wrong, the government is having an impact here and this is positive for the economy. I'm very concerned that this could change if any of the government "help" is removed or investors demand higher rates and push mortgages rates over 6%. For example, in November we were to have the final expiration of the first time home buyer credit. Sales were pulled forward and suddenly we have a reported drop in new home purchases in November. The following Bloomberg article demonstrates what the threat of pulling stimulus does. A mad rush of buyers that would have bought anyway step forward to take advantage of the taxpayer-paid windfall, and then demand dries up in the following months (Cash for Clunkers anyone?). http://www.bloomberg.com/apps/news?pid=newsarchive&sid=al3GTnIut0Ao

Obviously I'll have this prediction in my top predictions for 2010, but I'll suggest here and now that we have a dip in the sales trend in existing homes as much of the inventory that has been clearing has been foreclosures and investors (not occupants) have been swooping in to pick them up. Hopefully those investors have been buying smart and have deep pockets because I will predict that we'll see the new generation of home flippers that have emerged get sunk in 2010. They'll find that there won't be many buyers for these homes when mortgage rates hit 6% or 7% since we're all spoiled and believe that 4.75% is what we should expect! These investors will also get hit hard when banks like Wells Fargo and Bank of America actually release their piles of inventory instead of letting them trickle out. Look for these inventory clearances after 1st quarter reports come out.We were told that housing is the key to recovery - housing has not recovered yet, so I guess there is no recovery yet.

D) The Obama administration got in the act and began programs like the Housing Tax rebate for first time home buyers, Cash for Clunkers, and now Cash for Caulkers. In addition, the federal government has continued its payment of extended unemployment benefits. In addition, as a country we are now running a huge fiscal deficit (nothing new, just the magnitude of it is) and our government's expansion has required us to raise the debt ceiling (allowable debt of the country) to $1.8 Trillion Dollars! This doesn't even account for the addition of any new health care program or new stimulus. As I've mentioned several times, I believe that the Fed and Treasury must be cussing the administration for their interference. The Obama administration has kept to their strategy that they wouldn't waste any crisis and by goodness they haven't. In the hysteria they have continued to plunder the US taxpayer and add more programs and benefits to the entitlements for anyone that will take them.

We are now seeing that COBRA subsidy benefits are being extended to the unemployed (they have been offered for 9 months) and will be provided for another 6 month period. The program pays 65% of the premiums that someone that has been laid off of work must pay to keep their health insurance. It seems odd to me that the US Government and US taxpayer would pay for health plans at rates that are significantly higher than what can be obtained by families in the open market with individual policies. Of course we shouldn't be amazed at all about this, this is what happens when government makes decisions. This one example illustrates how the new health reform plan cannot and will not be an improvement or a cost savings for anyone.

While Obama has added his pork to the budget, the US treasury buyers will not tolerate the bloated debt of the USA. The market will require higher rates of interest and this will cause significant pain for all of us.
Crisis Management- Administrations have added pork laden projects and plans to the backs of taxpayers as an excuse to stimulate the economy. There are no plan for fiscal restraint or management of the budget. What simply blows me away is that I hear Obama speak about finding waste in government programs to pay for more stuff! Where is the idea that you cut costs and if necessary, benefits?

I'll comment more about the health care reform bill in another post, but you need to understand that the winner here is the health insurance industry (for now). As these bills are written they will have a captive audience of buyers. Many of you know that I own a health insurance brokerage and I saw a huge swing in commentary by insurance companies. If you don't think they are giddy, you are WRONG! Check out this email link I received from Aetna. These guys were hammering the Senators and then suddenly came out with this gem. Mind you, if this goes through I hope to sell everyone one of you a policy because I would hate to see you go to jail or pay stiff fines, but everything about this stinks and reeks of over promising and under delivering at a terrible cost to tax payers. A key provision in the plan is the elimination of pre-existing conditions as a basis for exclusion or rating up. Once this exclusion provision is removed we will witness the elimination of INSURANCE! Why would you obtain insurance till you have something serious now? GDP was revised downward and we are seeing that the government is responsible for most of the production for last quarter. I understand that

For all of these programs, what are the results? - We were told we need these programs to stimulate the economy- all have been short term and have done nothing to change the fundamental situation. We still have 10% unemployment and 17% U-6 unemployment. We were told that everything would begin to get better once housing is stabilized, we haven't seen housing stabilize and won't for a while. More appropriately we'll see things stabilize when people have jobs.

E) The accounting standards board (FASB) bowed to pressure from financial institutions and our government by suddenly recommending that accounting standards be thrown out the window. The accounting standards board have been complicit in this crime against investors as the boards were threatened and frightened into thinking that they would be responsible for imploding our economy. Where is the leadership in our country? I am afraid that the move to take a time out on reality simply makes it easier to do it again. The accounting standards board should have stood up and emphatically stated that accounting standards don't change or take a time out because the truth hurts! Future collapses will be much worse because the ponzi schemes the government and banks have set into motion were not stopped here. Clearly now that the banks are bigger and risk more concentrated similar meltdowns will be even more destructive. Accounting standards were thrown out resulting in a lack of understanding of true value of banks and insurance companies.

Where are we now? We still don't know what banks are worth and they are still raising capital and still lying about the risk on their balance sheets.

F) Finally, as we saw in the previous October post called Public Enemy #1-Deflation we see that the Fed and Treasury unleashed its last desperate weapon, Dollar Devaluation. The dollar devaluation trade is simply a move to destroy the value of the dollar relative to other currencies. This makes our dollars worth less and hence our debt worth less. We could also argue that it makes our goods cheaper as we hope to sell them abroad. The Fed has been true to its words that it would implement this strategy if faced with the prospect of deflation. When the government went to work in March the DXY was at $89.20 and they did not disappoint. They have moved the value down by as much at $15.00. The DXY is now trading at 77.64, well off its lows of $74.27 in late November and early December. So as the dollar has been pelted since March, EVERYTHING has gone up. Think about it, stocks, bonds, bread, gas, oil, gold, and the kitchen sink have all increased. http://www.marketwatch.com/investing/index/DXY/charts?chartType=interactive&countryCode=us So now, we've been told that everything is better and that we are recovering. In fact about 3 weeks ago, we had a surprisingly strong jobless claims report that stunned the market and boom, the dollar reversed course and interest rates began to rise. They rose because the strong jobless report indicated that things were stronger than expected and the Fed might need to remove stimulus (increase interest rates or as we know it, take the drugs away from the addict). Since that day there has been a resurgence of the dollar. Bernanke tried to tell the market that they would not raise rates because there were no indications of inflation in the market. Fed governors tried to tell us there was no evidence of inflation, and now Geithner has come out and told us that there is not a chance that we'll have a double dip.

So why are rates starting to rise and the dollar increase? How have we seen the dollar rise and the markets increase? First we have had some credit issues with Dubai, Greece, and Spain. All of those have reminded investors that there really is risk in the credit market and we aren't fully recovered. Scared investors tend to go to safety, and therefore we have seen a flight to safety in the dollar. Having said that, treasuries are a poor investment as the Fed has made sure to destroy any reality in that market (and value too). Therefore it is easy to see how liquidity could move to other dollar denominated assets allowing for the strengthening dollar AND rising equities and bonds (at least here in the last few weeks). Remember, this move up in interest rates and increase in the value of the dollar is contrary to what the Fed and Treasury desire (even though they say they want a strong dollar for the sake of our Chinese buddies). The increase in rates immediately translates to greater borrowing costs for the tax payers AND devalues the value of the treasury assets we already own. The government states that it wants to keep rates low to stimulate lending, but I can also see that we need to keep rates low to keep from blowing our own foot off since we have been purchasing our own debt through quantitative easing. Zerohedge has another good post that captures exactly what I've been saying and leading up to here.

What are the results? - So we have an administration that says they want a strong dollar, but we have a Fed Chief that has stated his strategy to save the economy would rely on a devaluation of the dollar. We have had an engineered rally in all asset classes and treasury rates that are way too low for the risk and duration of the trade. In essence we have a bubble in Treasuries!
My isn't it obvious, where ever we see the footsteps of the Fed, we see bubbles? So what is on the horizon for the Fed and Treasury? In 2010 we will see greater rates as buyers decide to wait it out and purchase their mis-priced treasuries at a better risk-reward. The greater rates will hurt bond holders and most of all the US tax payer. The bond market at some point will change the behavior of our current administration and the corrupt politicians that look to hand out entitlements and lack the idea of being representatives of the people.

We will see drastic cuts in city and state budgets and services before we see anything on the Federal side, but cuts will come at the national level.

If the Fed and Treasury want to keep the charade of low rates going then a fall in the equity markets will be the mechanism to deliver lower funding rates, unless they announce a new set of Q.E.

To wrap this up, we see that in each instance the failed efforts of the government to fix the situation have either simply done nothing or helped to kick the can down the road. As we've elaborated since our first post in August, the game of extend and pretend has been in full force. The problem is that at some point (2010, 2012, or 2015....) there will not be a way to extend it and a creditor will call our bluff and call in our debts. What I am really longing for is for a responsible leader to stand up and say NO, we won't offer this entitlement, no- we are actually going to cut services. Americans are going to be forced to live through these boom and bust cycles at an increasing level of speed and magnitude because our current leadership will not speak truth. The best result of all of this crisis is that average Americans are beginning to wake up and live a paradigm based on their needs and not their wants, based on their own ability and assets, not based on what their neighbor has. I am seeing a genuine reversion to true values of healthy financial management in peoples financial lives and in their businesses. Unfortunately, they had better be ready quickly because our government is saddling them with more debt and taxation to pay for promises and entitlements we can't afford. As an example of the crisis that consumers are facing check out this closing study.

Almost half (46%) of 2,148 consumers surveyed recently said they weren’t confident they could come up with $2,000 within a month in a crisis–from savings, family, friends, credit cards or other sources.Even among those earning $100,000 to $149,000 a year. almost 25% doubted they could raise it, according to the survey conducted by research firm TNS with academics from Harvard Business School and Dartmouth College. “We wanted to know if people could fix a broken car or furnace,” says Harvard finance professor Peter Tufano, who adds that most studies he has seen measure “how much cash people have… not how much they can access.” The survey results surprised him. “The ability to cope with emergencies is much less strong than we might have thought.”

I saw this in reality as people in the South dealt with Hurricane Ike. After 1 day people were cashless and without resources to make it through this terrible emergency. Americans need to wake up and save and communicate to their leaders that it is unacceptable to continue in this fashion. We had a final emergency and the US leadership chose to fake it till they made it rather than employ real fundamental solutions to problems of our own creation. At the end of the day I feel like the Bush Administration, Obama Administration, Treasury, and the Fed have just tried to spin whatever story we would fall for in order to get us to give them time. What they have figured out is that we just want them to give us something to believe in to quote a favorite from Poison (yes, I'm still into 80's hairbands). Guess what, they've given us a few tales, let's hope that no one actually figures out that what we've believed in isn't worth the trust we've placed with them.

Goatmug