Showing posts with label KSU. Show all posts

Monday, March 14, 2011

MARCH MACRO UPDATE - ALL SIGNS POINT TO WHERE?

We've experienced a 3% drop from the highs since February 18th.  While the 3% drop isn't too significant it certainly feels different than trading has felt over the last year or so.  The fundamentals continue to show a mixed to improving economy although the fuel that has propelled the economy over the last several months is schedule to be discontinued by June when QEII will be halted (perhaps).

Over the last month we've seen surging food and commodity prices that have been been the final straw that unleashed riots and discord throughout the middle east and emerging world.  Oil pierced the $100 level and now we must keep in mind the impact that these high costs will have on the fragile economies of the world.  Finally, the Japanese quake and unfolding disaster there will make the world economy more nervous than ever.  

TOTAL RAILS - http://railfax.transmatch.com/
Rails continue to outpace last year's tonnage with the exception of a downturn in grains and food transportation.


RAILS - AUTOS
We have seen an increase in autos that have been shipped in the last week.


RAILS - SCRAP
Scrap shipping continues to be just on pace with last year.


CANADIAN PACIFIC -
CP has recently underperformed last year's shipping totals and that continues to be the case.  In fact, CP's stock price too has been lagging relative to those other rails and has dropped more significantly compared to the likes of KSU or CSX. 


SCRAP INDEX - http://www.scrap.net/cgi-bin/composite_prices.cgi?id=100000&num=5
The Scrap Composite Index showed its first drop since the second quarter of 2010.  It does appear that there is a seasonal component to the drop if you look at the previous year-end, but it is worth watching. 


HOME PRICES - http://www.realtor.org/research/research/ehsdata
NAR reported another drop in the average home price for the month of January to a shocking $206,700. 
The highs in July of 2010 were pegged at $231,700 which highlights the correction we've seen of $25,000!  If you recall the months of June and July were the cutoff dates for the first-time home buyer tax incentives where buyers could get an extra $6,000 to $8,000 towards their home purchase courtesy of the US government (you and me).  What a complete waste!  We are now below the February 2010 lows.  In other words if you were dumb enough to buy a home based on the home buyer credit, you are close to being underwater.


MOODY'S /  MIT TRANSACTION INDEX (COMMERCIAL REAL ESTATE) - http://web.mit.edu/cre/research/credl/tbi.html
The Moody's MIT real transaction index dipped in December by almost 1 percent, although the entire 4th quarter was quite strong.  In total, the rally is not impressive, yet you've got to keep hope alive and any rebound is great.


MONSTER JOB INDEX - http://about-monster.com/employment-index
The Monster.com Job Index rose to a level of 129 in the month of February which is a 7 percent increase over the previous month.  The year over year growth is only 4%, but is positive.  The rebound is needed as it halted a 4 month slide.  The number of listings are well below the September 2010 levels.


FOOD STAMPS (SNAP DATA) - http://www.fns.usda.gov/pd/34SNAPmonthly.htm
December's SNAP (Foodstamps) data release shows up that there is no let up in the amount of Americans that are taking the government up on available programs to feed the poor.  December showed a 1.12% increase over the previous month and now indicates that there were more than 44.1 million people accepting assistance which is a 13.1% increase from the beginning of 2010.  Back in October of 2010 we saw a slowing in the rate of folks on the food stamp roles, however December marks the second straight month of an increasing rate of usage (the rate of change is increasing).  Obviously this information is dated and hopefully the numbers out of the Monster Employment Index can arrest these startling figures.  My heart is breaking for these people.  If you have any desire to see what is happening right here on US soil to your nation's children, please see the post we completed earlier this week - POVERTY IN THE USA - WHAT NO ONE WANTS TO SEE.


CFO OPTIMISM SURVEY - http://www.cfosurvey.org/11q2/PressRelease.pdf
The Duke / CFO Magazine CFO Survey was released last week and it shows that the bean counters in American businesses are more optimistic than last quarter about the economy.  They also suggest that capital spending will increase, and they predict that dividend distributions will actually be much higher.  There were a couple of reasons to pause though as they stated that they don't see much improvement in the job outlook and that any evidence of inflation could damage their outlook.  Hum.  It seems like this is more of the same here.  Company makes more money, company does not hire more employees.  One other note, the firms CFOs stated that credit conditions were improving, except for smaller firms.   


UCLA FUEL INDEX SURVEY - http://www.ceridianindex.com/
Growth in fuel usage has been slowing since January in this index.  This indicator usually follows movements in the overall indices and therefore I do not use it as a predictive tool, but more of a confirmation of overall economic activity.   


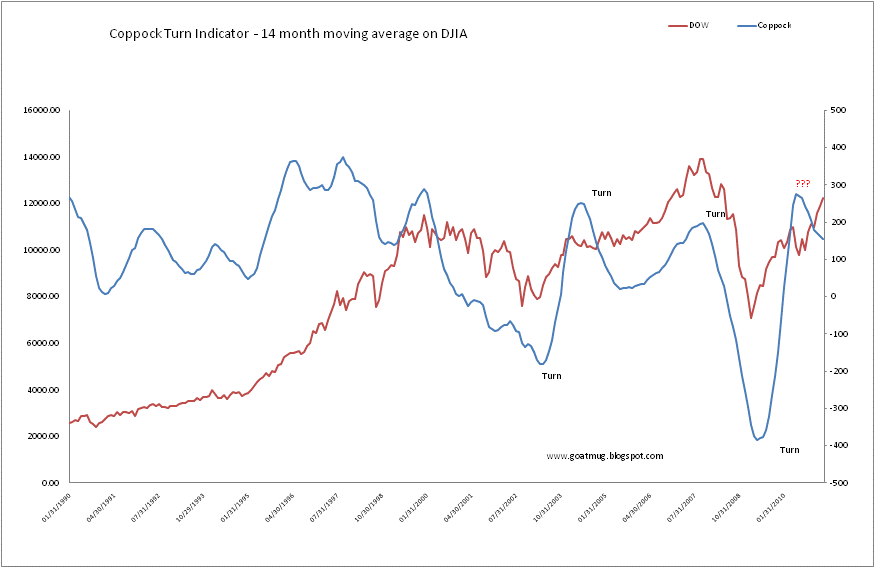
COPPOCK TURN INDICATOR
The Coppock Turn Indicator has stubbornly held its negative outlook since it flashed a sell signal all the way back in June of 2010.  If the Dow can move higher than 12125 to close for the month of March it will actually flip to bullish.  As I often comment, I think we've seen that the Coppock is pretty unreliable, but I am keeping it updated for entertainment purposes only.  Perhaps we'll see the Dow at 10500 again soon, but clearly the indicator missed out on a 2000 point ride north since then.
US FINANCIAL CONDITIONS INDEX - http://www.bloomberg.com/apps/quote?ticker=BFCIUS:IND
As we have seen over the last several months, whenever the US Financial Conditions Index eclipses the 0.0 mark it stalls out.  The zero level indicates that the economy is expanding, thus leaving recession behind.  Each time we've seen the FCI hit the 0.5 level it is slammed back and these last several weeks have been no exception.  I perceive this as a warning sign that the economy is still not out of the woods, although perhaps another $600 Billion of QE III might get us up to 1.0 at least, don't you think?  As of Friday the index was back at 0.148.


BALTIC DRY GOODS INDEX - http://www.bloomberg.com/apps/quote?ticker=BDIY:IND
The Baltic Dry Goods Index did see a reversal over the last month and has rebounded strongly.  I am guessing that part of the rebound has been directly related to stockpiling of dry goods such as grains as a result of the unrest in the Middle East.  The timing looks pretty good as an explanation for the significant move up in spot rates.


US DOLLAR - http://www.bloomberg.com/apps/quote?ticker=DXY:IND
Is that a tick up I see?  Strange.  While it is odd to see the dollar move up, I would suggest that this actually could be something we might see continue for a week or two more as this correction in equity markets develops.  We did see the dollar fall on Friday.  The dollar is at a critical place here where it needs to find support.  If not, we could easily see it usher in a new blast lower to areas not previously seen.  The push lower would cause renewed spikes in precious metals and other commodities like copper and oil.


6 MONTH LIBOR -  http://www.homefinance.nl/english/international-interest-rates/euribor-rates-6-months.asp
As we noted earlier last week, 6 Month Libor continues to move higher.  There have been rumors of interest rate hikes in Europe, as a move to stave off inflation, but the weakness in the banking system there simply makes me think that it cannot be done.  We are seeing lots of talk, but little real action.


TRADING UPDATE
In favor of getting this post up for the beginning of the week I am going to cut things a bit short and make every effort to post over the next couple of days a deeper look at specific areas where trading is at a critical juncture. Overall, markets for the last couple of weeks seem to be consolidating and trying to churn through some new selling. The selling hasn't been overwhelming, but heck, it is new to actually see selling! Remember, in our 2011 Forecast we identified March as a critical month due to the idea that big players would not wait to exit markets as QEII terminated. In other words, big funds and hedgies weren't going to wait for June to roll around before exiting positions. If the FED quits buying treasuries then that means that they quit exchanging those treasuries for dollars which somehow find their way into other speculative assets (food and other commodities anyone?). It would not be too hard to believe that we may see a decline in the thrust upward in many of these very frothy "investments" if the fund managers and primary dealers suddenly think that they may lose their source of fuel.
I don't want to get too over zealous though because markets are still weak enough that all it would take to see a huge snap back rally higher is an announcement from Fed officials that weakness is too great to stop these open market actions and QEII will actually be extended with a new batch of electronic cash. I also think that the Japanese disaster is just about enough of an excuse to put all free-market exercises on hold for another 6 months. There will always be a reason to extend an pretend as long as you have a printing press at your fingertips!

Overall, as I mentioned at the top of the post, information is mixed to improving. The overall job picture is getting better, but that doesn't mean that incomes are up. The CFO survey indicates that there are areas where there will be job growth, but as they see it, jobs won't be the big winner in the next quarter. Housing just can't get better and the decline in home prices are really troubling.

I will leave you with this last nugget that I put together with Robert Schiller's Irrational Exuberance data at http://www.irrationalexuberance.com/ . What I'm highlighting here is that we are at P/E levels that have been experienced around 6 other periods in the last 90 years. In each instance, stock markets corrected pretty significantly after those levels were reached. Now this is not to say that the correction is immediate (for goodness sakes, look at the 2000's!), but it is sort of like the treasury trade where we know that we are at historic lows and it is a pretty good bet that we'll see higher rates in the future. In the same manner, we know that we are at high P/E's and there is a safe bet somewhere and at some time that suggests that they will go lower and so will the markets. This is just one more warning that should be going off in our minds that there is risk in this system and we need to be fully aware that things could break down. The obvious question is simply when.


As markets open we should see Japan drop significantly with a carry through of the decline to as much as 10% in coming weeks. There will probably be a rebound due to printing of liquidity. One quick note on oil and other energy fuels, we should also see a drop in oil as there will be a drop in economic activity in Japan and Asia as a result of the disaster. I see this as temporary as the unrest in the Middle East is not going away and I continue to watch for the Saudis to demonstrate and attempt to overthrow their leadership. If any momentum is built in that country, oil and gas will rocket higher.


GOATMUG

Monday, March 8, 2010

MARCH UPDATE

MONTHLY UPDATE


Rail data continues to show improvement in total tonnage shipped. Last week each category of shipments showed higher levels of cargo traffic than the previous year in except for coal shipments. In comparisons to last year's data, coal and lumber are the only categories that are lower than 2009.


LUMBER & STONE
As usual, we are watching lumber and crushed stone to tip us off for some sort of housing and commercial building growth. Lumber is at least pushing higher compared to last year while crushed stone still tells us that commercial building is mired in the pit.


We want to watch what CFO's of companies are thinking and how they are feeling to give us an understanding of where they predict the economy may go. I like CFO's more than CEO's because typically CFO's are a conservative lot that see what is actually going on in the firm rather than projecting what may happen. In fact, CFO's typically downplay the strength of the company and I like that as they tend to reign in spending and the projections of the sales team.

A professor from Duke interprets the data here......

"The uptick in business spending indicates the economy has bottomed out. But the recovery might be short-lived if the employment picture does not begin to improve," Graham added. "Another note of concern is the corporate sector’s expectation to decrease inventories, exerting downward pressure on overall GDP growth."


EMPLOYMENT STABILIZING, BUT INVENTORIES TO DECLINE
About half of U.S. CFOs say they will increase full-time domestic employment in the next year, twice as many as say they will decrease their workforce. Net full-time employment is expected to increase 0.2 percent and temporary employment 0.5 percent. Finance chiefs expect outsourcing to rise nearly 4 percent.
"Certainly, it is good news that the employment bleeding has stopped," said John Graham, professor of finance at Duke’s Fuqua School of Business and director of the survey. "CFOs, however, still expect a virtually jobless recovery in 2010. Looking further ahead, it will be two to three years, maybe longer, before employment returns to pre-recession levels at most firms. CFOs say they are keeping workforces low due to weak consumer demand and increased efficiency in their production processes."

-- CFOs’ top economy-wide concerns include weak consumer demand, federal government policies, price pressure and credit markets. Top concerns about their own businesses include maintaining profit margins, low employee morale and liquidity management


No double dip - WLI data back up after 4 weeks of decline. Now at 129.8, the WLI is showing continuing strength in the recovery.


FINANCIAL CONDITIONS INDEX - http://www.bloomberg.com/


Like the WLI, the FCI is now solidly above 0 and this tells us that the "recession" is over. We will need to continue to watch the jobs data as this will be the issue that drags the economy down if people don't find jobs. As we marry this concept with what the CFO's are saying in the sentiment data above, we need to make sure that we are enjoying the "recovery", but are skeptical of it at the same time. CFO's are telling us that they are going to actually decrease employment and outsource more of their jobs overseas. That doesn't lend support to the notion that the consumer is back and that housing is fixed.


Speaking of housing, we are seeing pricing declines. While this sounds bad, pricing drops are the only way to make homes more affordable and accessible to buyers. Lower prices will help clear the shadow inventory of homes that will continue to suppress a recovery. Why our government continues to delay this is a mystery when we all know that the only way to fix the sickness is to take the medicine.


BALTIC DRY GOODS INDEX- http://www.bloomberg.com/

I've been watching the BDGI lately alot as an indication of activity of shipping in overseas markets. Spot shipping rates (not contracted ones, but the rate that you'd have to pay if you needed to ship something and lease your ship today on the open market) are moving higher, moving up some 10% from last month's report. A continued move here may bode well for some shippers. An acquaintance on www.slopeofhope.com sent me an article on how the pricing changes in the baltic dry goods index is not that connected to the pricing of the actual shippers, but no matter if that is true, this does indicate that commodities themselves are being consumed and moved. This bodes well for the continued move higher in emerging markets, basic industries, and commodities.


The dance continues. As we have concerns over debt defaults in countries like Greece, Spain, Portugal and Ireland, we see strength in the USD. When we get word that the EU, IMF, or Germans are going to bailout these countries, we then get a flight from the dollar and a recovery in equity markets. There has been some breakdown in the traditional relationship because not only are European investors fleeing the euro and other currencies, they are also simply buying US equities as well. This is why we've actually had some equity market strength in the face of concerns over Greece's sovereign debt problem. The nasty little secret is that all of these countries have been hiding debt and this is just coming to light. We will have a debt crisis, national governments are simply trying to do what they have done forever, ----keep the charade going as long as possible.

A story released this weekend is suggesting that Dubai actually has nearly 4x's as much debt as every thought as they have hid it. Doesn't that make you feel cozy inside to thing that national governments would like to their investors and debt holders? Why would banks and people follow laws and be honest if their governments don't lead by example.


Longer term, I still expect the dollar to rise and treasury rates to go higher as well. In the short run if we get a "solution" to the Greece issue, we'll see the USD drop.


TRADING UPDATE FOR MARCH
We've continued to rally since February 5th. I am still positive for the next month and 1/2 or two, but I am waiting to see a very slight pullback as investors will get overly bullish and everyone will lean to a specific side. Economic data will continue to surprise folks on the upside (jobs, housing sales, retail sales) and this could push the market higher. In addition, the resolution to the situation with the debt problems in Greece - although this is temporary because more countries face trouble. In spite of the negative potential news, slight pull backs have been tough to come by, so a good strategy may be to add purchases in an incremental fashion. Traders often call these time stops. Perhaps the timing could be to add every 2 weeks or every month. This way you don't put your entire holdings in at once.
WARNING - THE FOLLOWING ARE SPECULATIVE TRADES -
Emerging Markets - As we see continued USD weakness, we'll see momentum build in the emerging markets. I have had the following trade on for some time, but it just broke out today and I think it still has close to $1.00 more to run before hitting resistance.
EWM - Malaysia
Current - $11.30
Target $12.35 (Target Gain = 8.8%)
Downside stop - $10.50 (potential loss -7.1%)

Oil - I think oil continues to breakout. We are now above $80. As I stated in the beginning of the year, I believe we have a shot at $100.
GOLD - GLD - For a short time horizon, I believe gold is going higher. I am personally not involved in this trade and am not going to provide levels for a trade on this item despite it's positive direction. You can comment and leave me levels and I'll take a look to confirm it if you'd like.
(VXX) - (BEARISH TRADE FOR A PULLBACK) VIX is now at 17.8 as I am writing this. I do believe we could have a short term pullback and the use of VXX to play that would be ok. This is not a long term trade, you are simply trying to capture any downside as we've moved quite far since Feb 5th without a significant fall. Take a look at thetechnicaltake.com . Guy Lerner is again stating that bullishness is high and this should give us some validation to the notion that we'll make money as the fear index reverses and goes higher - making money in the VXX.

KSU - KSU is now trading above $35.00. I like the gains we took on it, and will wait to re-enter.
As usual, thanks for visiting and thanks for your comments.
Goatmug

Wednesday, March 3, 2010

CAN THE "FEAR INDEX GUIDE US?" - VIX REVISITED

Just a quick note about our old friend the VIX. We've rallied back quite well and all still seems to be going according to the plan we've laid out where we see some strength in the market for the next 6 weeks or so. Now the jobs report could come out extremely weak since (and blame it on the snow of course!) but still there does seem to be strength in the market in a broad based rally that has included home builders, retailers, technology, metals, commodities, and energy.
Despite things going as planned, I am still cautious and looking for indicators in the market that may give us a warning that the run is over done.


I have noticed that transports like KSU seemed to have hit the wall over the last two days, so that may be an indication of some weakness or some consolidation. As you know, the KSU trade in my opinion has past and I sold out of that earlier. Some might say too early, but 10% gains in little over a week are great and I didn't want to give them back. Having said that there has been some real stiff resistance right at the $35 area where I highlighted in the chart. By the way, don't over do your trade size. I received a comment from a visitor that told me that he had completed the KSU trade and it was HUGE. Do not purchase a particular stock in such a large portion that it becomes a significant or oversized holding in your portfolio. You must manage risk in many ways and the worst thing you can do is to take too large of a position.


Anyway, I mentioned that P/Es were way too high the other day and another item I'm watching is the VIX. The VIX is the fear index or really a measure of the volatility in the market. Since February 5th the market has pretty much rocketed in one direction and therefore fear has almost disappeared. As usual, my friend Guy Lerner at thetechnicaltake.com has highlighted that the smart money and insiders are beginning to sell and the dumb money is very bullish. These are the times we need to wake up! The VIX is now reading 18.83 and this is an indication of complacency in the market. I have mentioned a trade to buy VXX on a bet that the market will reverse and fear will flood back to the market. I think we are getting close to a good risk/reward area to put that trade back on, but I will hold off a bit as I've mentioned before in the comments section, I'd like to see it with a 17 handle. We won't need to go much higher in the market to get to that level.


I hope the attached chart is clear. Click on it to enlarge it, but this is a 3 year picture of the cash S&P 500 (SPX) against the VIX. I have marked each instance where the VIX traded lower than 19. I've also plotted points on the SPX so we could see where it was trading on that same day. (The tabletop line is the spot where showing the value of the SPX rather than the bold dot. The capture software I used moved the dots around, so please use the white line as a graphical indication of where the text values should be). I think the information is pretty compelling that it may make sense to bet that the market will reverse sooner rather than later. Yes, the market can continue higher, but again the VIX is warning us that EVERYONE thinks it is safe in the water, and that is usually when the sharks attack.

Finally, some will say that the last 3 years is not a great sample of to use, but I have two ideas that counter that notion. First, even the most recent correction on January 19th hit a level on the VIX around 17.50 and resulted in nearly a 100 point drop or 8.5% fall in the SPX or a purchase of VXX would have gone from around $27.00 a share to $33.50 in just a few days. So we have recent history that highlights just how actionable this trade can be. Second, the market in the last year has traded in a fashion that is absolutely not normal. The market typically doesn't move in one direction for 10 straight months. Therefore I would suggest that we need to be looking at recent evidence in "this" market rather than long dated historical examples that might not be relevant.


Goatmug

PS - Note the cool little map at the upper right hand portion of the blog. Click on it and it shows a map of where all the visitors to the site are coming from. Thanks for visiting, I think it is neat that someone in Brazil and Indonesia have visited!

Friday, February 5, 2010

February Update

Ok, here's a quick update for February.


RAILS - (from Railfax) - http://railfax.transmatch.com/
The next few weeks will reveal how much of the recovery is real. As you can see, rail traffic is now on the verge of a breakout over last year's levels. To this point, all of the talk about recovery has been forward looking and full of "Hope". We will see the truth in the next two to three weeks.


Commercial and residential building is not showing up here in the shipping of lumber and crushed stone. It is very interesting to note though that home builders did not break through their lows in the correction over the last two weeks, and we are seeing lumber prices really catch a bid.


LUMBER PRICING
See futures trading charts.com - You'll see lumber prices have moved much higher and there is quite a bullish trend underway. They do not give permission to copy their charts so I have included a link here.

The question I am asking here is simply this - Does this move in lumber prices indicate some type of increase in demand that will translate into greater production for homebuilders and commercial development? Someone is buying so we should be looking at these types of investments. It is interesting to note the the XHB (homebuilder's etf - I'll add a chart later)
has not really broken down terribly over the correction of the last couple of weeks. This should be on our radar as a potential bullish breakout if the overall market gains traction.

Once again, KSU is back over last year's trendline in shipping. We might review how the stock is trading and attempt to go back to the well one more time.


Click on the chart for KSU - I see $29.00 as pretty strong support here. I might look to purchase the stock in the low $30.00 level with a target for exit at $33.50. Fundamentals coupled with the channel that remains intact will produce a good opportunity for a 8% to 10% move higher. As I mentioned, set stops at $29.00


The Baltic Dry Goods Index is continuing to make higher highs and higher lows. We'll continue to monitor this trend which indicates that a recovery in commodities and shipment pricing power is underway. It is important to note that a decline here below the $2200 level would indicate that commodity demand is drying up.

FINANCIAL CONDITIONS INDEX - http://www.bloomberg.com/apps/quote?ticker=BFCIUS:IND


The Financial Conditions Index dropped back below zero (0) last week with the market correction. The message here is that we are not out of the woods yet and the recession is not completely over. A strong move over zero would allow us to declare everything is better. As you know, I question the FCI simply because more than 1/2 of its components are Fed liquidity driven, meaning that the slosh of funds provided by our generous Federal Reserve are being captured in many of the inputs here.


The dollar has been the beneficiary of strength due to the concerns with the debt of several European countries - namely Portugal, Greece, & Spain. Recall we had similar issues with the debt of Dubai just a month or so ago. As investors fear uncertainty they flood back to the good old greenback and typically buy US treasuries. They aren't buying treasuries because they yield a bunch or as we've discussed, compensate them for the actual risk they are taking, they are merely buying the dollar because it is the best of the bunch.
What has been the result of this 2 weeks of dollar buying? The obvious answer is just what we noted would happen. When the dollar gets stronger, EVERYTHING else gets beat up. That has included the overall equity market, the corporate bond market, gold, silver, and any other commodity.
TRADING FOR THE MONTH
Well, what is the strategy for this month? I think the best approach for this month is to recall the ranges we've previously discussed. Remember we've highlighted the upper boundary for the range at 1150, well we punched through the 1110 area on the S&P and now have a lower area of 1060 as a lower boundary.
As traders become more concerned about risks, they put more bearish bets on and that is bullish and portends a rebound in the market.
Greece is the near term catalyst for a bounce. If an announcement is made that protects or guarantees their debt we may see a jump. The EU needs to be concerned though because this will set in motion a precedent for further actions for Spain and Portugal which both are very sick.
If you have dry power left you might consider putting to work some of it here and looking at the same old items we've mentioned before (commodities and emerging markets). Don't forget that KSU trade either because it seems like a good set up. Finally, if you bought the VXX (fear index) I mentioned you made great money, you need to get rid of that because if the market bounces you'll start losing.