Below is a picture of TLT, the exchange traded fund that measures the long dated treasuries in the market (20 year plus). As I've posted before, TLT's breakouts in August of 2008 were a lead indicator for the stress in the equity markets and economy as investors fled to the "safety" of US government treasuries.
As we see in the chart below, I warned a month or so ago that the push up in prices (yields going down) was a warning of bad things to come. Well, once I posted that we had a nice recovery in July and the price on TLT dipped back below the 100.15 level which I highlighted as the warning line.
Last week, the Fed announced that they would begin re-buying treasuries when some of the mortgage debt they owned rolled off. In essence, they wouldn't allow their asset holdings to go away, they would simply find a new home for any money that was repaid. (I think of it this way - that the Fed is not going to give our money back, we gave it to them (taxpayer guarantee of printed money) and instead of returning it once the stated use of the dollars is complete, they are going to recycle it into purchasing treasuries.
Well, because the Fed told the world they'd buy treasuries and even highlighted which ones they'd buy, the market, (investment houses and brokers), has done what any group of smart investors would do. They have rushed in and purchased these securities ahead of our government! Yeah! Isn't it neat to know that our government is so generous and willing to buy over-priced treasuries from these savvy traders?
So, does the move in TLT signal that the market is melting down, or does it signal that the FED is just stupid (or manipulative) and created a rush into that market? The answer is probably mostly the second and a little of the first. Here's what I mean. By telegraphing its intentions to purchase new securities with the roll off and then describing which ones it might buy, the Fed has really begun to achieve its goals. (They are not stupid, they are being manipulative).
First, the headlong rush into treasuries from other participants has further lowered interest rates to all time lows and this allows the government to fund our crushing debt at a much lower cost. The by-product of announcing this is that there are some hedge funds and investors that are simply gun slingers that are looking to make some quick bucks front-running the FED. The recent action in TLT especially today is probably mostly attributed to these fine fellows.
But, there are some folks that simply are so afraid of a collapse in markets that they are a new class of buyers of treasuries that have never done so. Think people in 401Ks and retirees. These people have lost 40% or 50% of their portfolios since March of 2000 and have endured this terrible market. They are vowing not to get crushed again. (They might get crushed again if interest rates rise). The surge in TLT starting in June can be largely attributed to a large amount of folks retreating from the markets entirely, shunning equities and desiring the safety (hopefully) of fixed income. This is why corporate bonds as well as treasuries are at extreme lows in yields.
So, whats next? Well, as we've said many times, the Fed wants low rates to get the economy going (even though it has not worked). They are so fearful of deflation that they are doing anything and everything to try to stimulate the economy. Is the run in treasuries over? No yet in my opinion. As I've said, we will see 3.0% 30 year mortgages in the next year or so. Rates for treasuries will need to go even lower than the current historic lows to get us that gift (if you can qualify for a loan that is).
In the longer term, will buyers of treasuries get hurt? Heck yes!
Will the move in treasuries lead to a move down in the market? Possibly. I'm not 100% convinced. The argument to support the decline would be any move down that gets going could be met with an absence of buyers as they'll have committed resources to easier leveraged trades in treasuries. In addition, if you think about it, a strong move down would actually make these buyers of treasuries even more money as a drop in markets have have others coming into treasuries looking for a safe haven. Wouldn't it make sense to create a market sell off if you had the capability to move the markets?
Why am I not 100% convinced? Last month, I suggested that the Fed would do some type of stimulus and therefore if effective they would attempt to juice the market via use of extra dollars sloshing around to purchase equities and other assets, or effectively the devaluation of the dollar. This is why I said that purchases should be made overseas and in commodities like gold and not in US markets. I'm still in the camp for the month of August that this should be my approach.
No matter what, the take away here is just another demonstration of how inefficient government is. When the Fed purchases these bonds, they will be buying at higher prices than 1 week ago due to their prior-signaling of their intended course of action. Of course this is purposeful and their attempts are made to manipulate the market and keep rates artificially low anyway, so what's wrong with overpaying for $200 Billion in bonds between friends anyway?
GOATMUG
Monday, August 16, 2010
Friday, August 13, 2010
WHAT'S UP WITH EURO - LIBOR 2 MONTH RATES?
Just scanning some of my normal indicators and found something odd in 2 month Euro-Libor rates. While everything in banking land looks and feels great (RIGHT!!!) and all rates have been coming down for at least 5 to 6 weeks, the 2 month Euro-Libor rate has started to move higher on 8/5/2010.
All other time periods continue to show funding rate improvement, so I don't want to over do the alarm here, but this kind of nugget would help us identify trouble in Europe if on the odd chance that perhaps the bank stress tests over there didn't really clear up anything. I mean, can you imagine a stress test where regulators didn't actually stress anything but the market just rallied because someone told them things were better? No, I can imagine anything like that either!
Here is the data summary so you can see the trend in rates by day.
08-12-2010 0.67313 %
08-11-2010 0.67313 %
08-10-2010 0.67063 %
08-09-2010 0.67063 %
08-06-2010 0.67063 %
08-05-2010 0.66938 %
08-04-2010 0.66750 %
08-03-2010 0.66875 %
08-02-2010 0.66875 %
07-30-2010 0.66750 %
I'll keep watching this as an indicator that banks begin to not trust each other. As concerns re-emerge about the health of sovereign country debt in Europe we'll see pressure on European banks too.
GOATMUG
All other time periods continue to show funding rate improvement, so I don't want to over do the alarm here, but this kind of nugget would help us identify trouble in Europe if on the odd chance that perhaps the bank stress tests over there didn't really clear up anything. I mean, can you imagine a stress test where regulators didn't actually stress anything but the market just rallied because someone told them things were better? No, I can imagine anything like that either!
08-12-2010 0.67313 %
08-11-2010 0.67313 %
08-10-2010 0.67063 %
08-09-2010 0.67063 %
08-06-2010 0.67063 %
08-05-2010 0.66938 %
08-04-2010 0.66750 %
08-03-2010 0.66875 %
08-02-2010 0.66875 %
07-30-2010 0.66750 %
I'll keep watching this as an indicator that banks begin to not trust each other. As concerns re-emerge about the health of sovereign country debt in Europe we'll see pressure on European banks too.
GOATMUG
Labels:
banks,
Euro-BOR,
Libor,
stress tests
Tuesday, August 10, 2010
THE US IS BROKE - Bloomberg Opinion - Can I Get An Amen?
Normally, I'd write a long blog post here and tell you why I believe the US is on its way down the path of destruction by promising too many benefits, collecting too few taxes, and allowing too many thieves to hold political office.
Today, I will defer to another and allow him to persuade you with his gifted rant. Professor Laurence Kotlikoff of Boston University just hits you with many of the facts and a heck of a lot less angry finger pointing at the political class than you'd get from me.
Enjoy.
Bloomberg Opinion - US IS BROKE
GOATMUG
Friday, August 6, 2010
BROTHER CAN YOU SPARE SOME CHEESE?
Well once again we are provided another slug of data from our friends in the food stamps program. All the recovery our President is telling us we are seeing obviously hasn't dribbled down to those that require assistance for food and diapers and other necessities. Of course this data comes from May, but weren't we told to expect a turnaround somewhere? Perhaps it will come next month......(holding breath now).
As you have already read the weekly jobless claims were remarkably worse than expected and didn't produce the number of new jobs we were anticipating. I guess we need more folks our there caulking homes and weatherizing them so we can get our houses all green and stuff.
While we wait for next month's improvement here is a nice little chart which shows how much better things are getting.
May 2010 Highlights
40,800,000 people participating
18.9 million households
$5.45 Billion in annual costs
$289 cost per household
GOATMUG
Labels:
foodstamps,
jobs,
SNAP
Wednesday, August 4, 2010
THROWING DOWN THE GAUNTLET - AUGUST MACRO REVIEW
RAILS - http://railfax.transmatch.com/
We begin this month's review looking at rail traffic. Rail traffic in general continues to improve over 2009 levels. Because there are some seasonal issues going on around this time, I don't want to over-hype the small draw down that we are seeing here. Seasonally adjusted we are only down around 1.3% in total tonnage from last month. Having said that, every report I read is simply talking up how great the shipping tonnage rates are. In an attempt to examine this, we can simply note that tonnage compared to 2009 is about 20% greater yet it is still around 10% lower than 2008. In addition, we need to keep in mind that the best years on record for intermodal rail shipping were 2006 and 2007 so it is a bit more sobering to think that we are recovering, but not near peak levels.
GDP adjustments really reinforce this as last weeks revisions to GDP showed that growth in GDP was slowing well before 2008.
RECESSION INDICATORS ON RAILS -
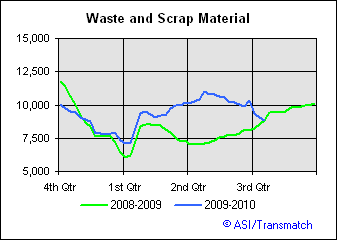
Motor Vehicle rail cargo and waste and scrap metal materials shipping is tailing down in recent months. The autos shipping and sales data is absolutely seasonal so I don't want to highlight that much given that it may mean nothing, however the drop in scrap metal and waste movement is something to keep an eye on as these are inputs into the manufacturing process. Later we'll look at scrap metal pricing.

ECRI / WEEKLY LEADING INDICATORS and ECRI GROWTH RATES - http://www.businesscycle.com/resources/
ECRI continues to release data showing that the weekly leading indicators are falling. Last week's -10.7% growth rate provides ammo to those that are arguing that we are headed for slow down, if not another recession. Again, the slowing data here is in contradiction to the ever-ramping stock market.
Housing drops and consumers reducing their purchases is driving the drop in growth rates.
ST LOUIS FED PRESIDENT BULLARD THROWS DOWN THE GAUNTLET -
As the flood of disappointing news rolls in about a slowing economy, St. Louis Fed President James Bullard moved from his centrist position to one of outright advocacy for the spawning of the Son of Stimulus just like we've been warning for at least a month. Bullard's discussion warned of the specter of a Japanese style deflation, exactly what they want to avoid at all costs. Bullard's comments make it all the more likely that the Fed will actually move to invoke more stimulus in the form of buying treasuries, buying more agency backed mortgages, and maintaining a near zero rate (no hikes).
Bullard's comments probably are part of an orchestrated effort to convey the Fed's future policy. We cannot forget that no matter how ineffective Fed policies have been in creating a real recovery in the economy, this is really about creating a rebound in market or asset values. Like we've stated above, Good Time Al believes the market IS the economy. Check back to the post we made last year regarding Bernanke's 2002 deflation speech. There is no ambiguity there. He is positively stating that the Fed can and must win against the deflation enemy. Despite the fact that jobs have not returned and the housing market is still floundering, we will see a new round of QE that looks to further juice the market. I would guess that this will have a smaller effect in terms of the magnitude of a move on the market and the impact will have less of a lasting effect in terms of time than last time, but if we get confirmation from the Fed that they will provide liquidity, we will see a move up.
This further highlights the notion that we will probably see mortgage interest rates at 3% or 3.5% in 2011. Isn't it funny how despite their efforts we continue to spiral the way of Japan. Want to get an idea for what it might look like right now? You can buy a Japanese 10 Year note and receive 1% on your money! Hello deflation! PUBLIC ENEMY # 1 - DEFLATION
I'll remind you the futility of the game that the Fed is playing - FDR’s Secretary of the Treasury, Henry Morgenthau came to in 1939 after initially being a proponent in massive fiscal stimulus to cure the depression and employment. His comments are provided below:
"We have tried spending money…We are spending more than we have ever spent before and it does not work. I say after eight years of this administration, we have just as much unemployment as when we started… And an enormous debt to boot!”
30 DAY TRADING OUTLOOK- Ok, so the Fed is beating the drum that they will do anything to stop deflation and they will continue to buy treasuries, what is the play for the month? It is exactly the same strategy that I outlined on July 3rd in the Mid Year Review. We should continue to invest in emerging market issues focused in countries like Brazil, China, India, Indonesia, Malaysia, Chile, and Taiwan.
All of these etfs have broken out, and even the S&P 500 extended its gains over the 1120 level I highlighted last week. While macro indicators confirm the slowing, we cannot deny the short run impact of a committed Fed. Bullard essentially has thrown down the gauntlet and stated that the Fed will use all of its ammo to fight deflation. Once again, the Fed playbook is opened and I suggest you read our post on deflation to remind yourself of the commitment to defeat that enemy at any cost. The hawkish tones of Bullard emphasize what is at stake and the intensity of the desire to prevail.
While I've been bearish on gold lately expecting a pullback to the $1040 area, I am tempering this because of the expected Fed devaluation. CPI data will probably come in lower, yet this will only fuel the Fed's aggressive response.
GOATMUG
We begin this month's review looking at rail traffic. Rail traffic in general continues to improve over 2009 levels. Because there are some seasonal issues going on around this time, I don't want to over-hype the small draw down that we are seeing here. Seasonally adjusted we are only down around 1.3% in total tonnage from last month. Having said that, every report I read is simply talking up how great the shipping tonnage rates are. In an attempt to examine this, we can simply note that tonnage compared to 2009 is about 20% greater yet it is still around 10% lower than 2008. In addition, we need to keep in mind that the best years on record for intermodal rail shipping were 2006 and 2007 so it is a bit more sobering to think that we are recovering, but not near peak levels.
GDP adjustments really reinforce this as last weeks revisions to GDP showed that growth in GDP was slowing well before 2008.
Motor Vehicle rail cargo and waste and scrap metal materials shipping is tailing down in recent months. The autos shipping and sales data is absolutely seasonal so I don't want to highlight that much given that it may mean nothing, however the drop in scrap metal and waste movement is something to keep an eye on as these are inputs into the manufacturing process. Later we'll look at scrap metal pricing.
THE WEAKEST SHIPPING TONNAGE - KSU
As I mentioned last month KSU and KSU Mexico continue their slide in tonnage. I put this up because we need to continue watching these rails and their cargo shipping. Specifically for them, they are encountering a crossover from levels from last year in this quarter and this may be a concerning development to monitor. Last month I mentioned CNI and showed their chart as the best performer. I also suggested passing on their stock simply to wait for a retest below support. That didn't work out well as the stock is now trading almost $6.00 or 11% higher. (I wouldn't chase it here).
I wanted to include some data related to jobs. Below is the information for the Monster.com Employment Index. This data shows a summary of online recruiting efforts and job availability. This data highlights information from June, but I will begin updating it monthly in my chart form. In that time period, Monster suggests that in 13 of the 20 major employment areas in the country, there were additional listings on job boards and company websites. The biggest gains were made in hospitality and food services industries. Examining the most recent unemployment report confirms these trends are continuing as well.

ECRI / WEEKLY LEADING INDICATORS and ECRI GROWTH RATES - http://www.businesscycle.com/resources/
ECRI continues to release data showing that the weekly leading indicators are falling. Last week's -10.7% growth rate provides ammo to those that are arguing that we are headed for slow down, if not another recession. Again, the slowing data here is in contradiction to the ever-ramping stock market.
Housing drops and consumers reducing their purchases is driving the drop in growth rates.
MOODY'S / MIT COMMERCIAL PRICE INDEX - http://web.mit.edu/cre/research/credl/rca.html
The most recent Moody's / MIT Commercial Price Index Data shows that commercial real estate prices in the index increased 3.6% for the month of May. Again, this data is lagging here, and isn't showing that pricing has leveled off yet.
FINANCIAL CONDITIONS INDEX - http://www.bloomberg.com/apps/quote?ticker=BFCIUS:IND
Equity market gains and other financial market rebounds have fueled the recovery in the Bloomberg Financial Conditions Index. A level above 0 would indicate that the recession is over, numbers below show a contraction. We have not pushed through zero yet, but a significant equity market explosion higher in August could at least give us a second attempt at moving into an expansionary number.
SCRAP METAL - GOOD TIME AL'S FAVORITE INDICATOR - Alan Greenspan often said that he watched the price of scrap metal to determine the health of the economy. Below is a scrap metal chart for the last two years. Just like every 2 year chart it shows the same shape moving up and to the right, but it is interesting to point out that this index bottomed out in January of 2009. This would have been a good indicator to use to portend the market's recovery in 2009. We see that we've endured a drop in scrap pricing in late June and July, only to see a move up in the last week or so.
The USD's dramatic decline seems to have washed away all fear of European collapse or should I say the lack of fear of the European collapse has begun to wash away the value of the dollar! Those stress tests sure did the trick didn't they? The decline of the dollar has certainly also ushered in a revival of the stock markets. Funny, we are now hearing that folks are concerned about the downward direction of the dollar. The truth is simply this in my opinion. We will have little upward momentum in the markets without a destruction of the value of the dollar. Having said that, Alan Greenspan this weekend put into words what the FED is really thinking. Greenspan simply stated that the market is the economy! So, we must be on alert that since the "Economy is the Market" we are being reminded that asset values are the only concern of the Fed and the only hope to return things back to the good old days. Understanding this means we remind ourselves that they seek a return to inflation, easy money and credit, and if it takes it, a decline in the purchasing power of the dollar. Here me loud and clear. There may be ups and downs in the value of the dollar, but if the FED has anything to do with it, there will be an ultimate walking down of the value of the currency. This is the only way to survive and extend with the looming debt issues we have.
BALTIC DRY GOODS SHIPPING INDEX - http://www.bloomberg.com/apps/quote?ticker=BDIY:IND
The BDI has made a significant drop since May and June and is attempting a bottom here. As commodity demand increases we should see a move higher in the cost of spot shipping, however the drop in the BDI is a reflection of the over supply of ships that stand ready to carry freight. Still, if you are an owner of those ships that don't have long term contracts at a fixed price, you are probably hurting very badly at these rates.
TRADING UPDATE -
I like the simple chart provided by the guys at Growthstock Advantage. Based on their indicator that examines the number of stocks trading above their 40 day moving average, the market is NOT overbought yet. As stocks get extended it is sometimes helpful to see when everyone loves the market. Typically you might consider scaling out of positions or shorting at that time. At this point the indicator is NEUTRAL.
C
COPPOCK TURN INDICATOR - I showed this chart last month and it is simply a 14 month moving average of the Dow. When the average turns and heads south like it did last month at the end of July, it is an indicator that the market may be headed the other direction. The COPPOCK is one of those indicators that confirms a move rather than one that is predictive. Having said that, even with July's monstrous performance, the COPPOCK is suggesting that we are still going to go lower and therefore it is BEARISH.
US Libor continues to improve and so do all other denominated Libor measures. I made a comment right after the European financial stress test result release that I'd be watching these levels to get a confirmation that the banks actually were believing what was being served up. Because we are seeing a drop in these rates we can confirm that stress is abating. So while the contraction in rates is only a few basis points since last week, it is a 10% reduction in 1 week funding rates, which is significant.
ST LOUIS FED PRESIDENT BULLARD THROWS DOWN THE GAUNTLET -
As the flood of disappointing news rolls in about a slowing economy, St. Louis Fed President James Bullard moved from his centrist position to one of outright advocacy for the spawning of the Son of Stimulus just like we've been warning for at least a month. Bullard's discussion warned of the specter of a Japanese style deflation, exactly what they want to avoid at all costs. Bullard's comments make it all the more likely that the Fed will actually move to invoke more stimulus in the form of buying treasuries, buying more agency backed mortgages, and maintaining a near zero rate (no hikes).
Bullard's comments probably are part of an orchestrated effort to convey the Fed's future policy. We cannot forget that no matter how ineffective Fed policies have been in creating a real recovery in the economy, this is really about creating a rebound in market or asset values. Like we've stated above, Good Time Al believes the market IS the economy. Check back to the post we made last year regarding Bernanke's 2002 deflation speech. There is no ambiguity there. He is positively stating that the Fed can and must win against the deflation enemy. Despite the fact that jobs have not returned and the housing market is still floundering, we will see a new round of QE that looks to further juice the market. I would guess that this will have a smaller effect in terms of the magnitude of a move on the market and the impact will have less of a lasting effect in terms of time than last time, but if we get confirmation from the Fed that they will provide liquidity, we will see a move up.
This further highlights the notion that we will probably see mortgage interest rates at 3% or 3.5% in 2011. Isn't it funny how despite their efforts we continue to spiral the way of Japan. Want to get an idea for what it might look like right now? You can buy a Japanese 10 Year note and receive 1% on your money! Hello deflation! PUBLIC ENEMY # 1 - DEFLATION
I'll remind you the futility of the game that the Fed is playing - FDR’s Secretary of the Treasury, Henry Morgenthau came to in 1939 after initially being a proponent in massive fiscal stimulus to cure the depression and employment. His comments are provided below:
"We have tried spending money…We are spending more than we have ever spent before and it does not work. I say after eight years of this administration, we have just as much unemployment as when we started… And an enormous debt to boot!”
30 DAY TRADING OUTLOOK- Ok, so the Fed is beating the drum that they will do anything to stop deflation and they will continue to buy treasuries, what is the play for the month? It is exactly the same strategy that I outlined on July 3rd in the Mid Year Review. We should continue to invest in emerging market issues focused in countries like Brazil, China, India, Indonesia, Malaysia, Chile, and Taiwan.
All of these etfs have broken out, and even the S&P 500 extended its gains over the 1120 level I highlighted last week. While macro indicators confirm the slowing, we cannot deny the short run impact of a committed Fed. Bullard essentially has thrown down the gauntlet and stated that the Fed will use all of its ammo to fight deflation. Once again, the Fed playbook is opened and I suggest you read our post on deflation to remind yourself of the commitment to defeat that enemy at any cost. The hawkish tones of Bullard emphasize what is at stake and the intensity of the desire to prevail.
While I've been bearish on gold lately expecting a pullback to the $1040 area, I am tempering this because of the expected Fed devaluation. CPI data will probably come in lower, yet this will only fuel the Fed's aggressive response.
GOATMUG
Labels:
Bullard,
consumer credit,
Coppock,
employment,
Fed,
gold,
Libor,
oil,
t2107 indicator,
USD,
WLI Data
Subscribe to:
Posts (Atom)