Showing posts with label CDS. Show all posts

Monday, November 7, 2011

KILLING THE BROKEN SYSTEM BY SAVING THE SYSTEM

UNINTENDED CONSEQUENCES STRIKE AGAIN
So, the question that has been on my mind over the last couple of days, "What Happened to MF Global? and also, "Why?"  We are finding out all sorts of details of mis-management and lack of risk controls at MF Global and the sheer arrogance of Jon Corizine at the helm of the firm. 

I suggest reading Felix Salmon's article at Seeking Alpha for a perspective on the firm.

http://seekingalpha.com/article/304132-what-happened-at-mf-global

Beyond this explanation I think it is important to go further because I believe this week is going to be critical for the markets, currencies, and global economies and we can lay the blame all at the feet of the Eurozone leadership and ISDA and their efforts to save their broken system by destroying their system.

EFSF AND THE GREEK BAILOUT
Remember two weeks ago when markets ripped higher because the Europeans finally came together and agreed to agree on things they would attempt to put together in the coming months?  Remember the Slovakia vote that paved the way for the EFSF and saving all of the Eurozone?  Remember how a 1 Trillion levered SPIV would be the catch all for crummy assets and remember how SOME institutional holders of Greek debt would suffer 50% losses and others 21% losses and even others, no losses?

Ok, so we remember all of that.  What I want to turn your attention to though is that despite the 800 point rally in the Dow in a mere week or two, despite all the agreements, we are actually in a far worse position in funding and liquidity terms than we were just weeks ago.  Why?  As part of the EFSF agreement, banks that form the ISDA (International Swaps Derivatives Association) colluded to state that the write off of 50% losses on holdings of Greek debt IS NOT a default triggering event for their purposes and for the purposes of CDS (credit default swap) protection..  Is this important?  Yes. 

CDS - INSURANCE COMPANY AND HEDGE FUND "INSURANCE"
If ISDA (the banks) can rule that the insurance protection you bought under a standard ISDA document (binding contract between counterparties- many buyers just use the standard contract instead of negotiating their own contractual triggers) even when the rest of the world knows that an "event" did occur, then institutional buyers that just took a bath and other potential buyers of sovereign debt suddenly need to rethink the risk that they have been acquiring in their portfolios. 

If their hedged portfolios are no longer hedged, why would you ever buy a Greek or Spanish or Italian bond?  The answer clearly is, you wouldn't. 

WHY WOULD ISDA CLEARLY LIE HERE?
ISDA would lie for a couple of reasons.  First, the banks would lie because they have written a bunch of this CDS as protection against a sovereign default.  While the total net exposure is probably not huge for Greece, we all know that whatever happens in Greece doesn't stay in Greece and it will be visited upon all of the PIIGS countries, so it is in the best interest of the banking cartel to rule that a 50% loss is not a default event.  If there is no default, they don't have to pay.

Second, a triggering event would immediately call for downgrades of other European banks like the French and German banks that hold alot of these bonds from credit reporting agencies.  Downgrades require more capital and the death spiral continues as the countries that issued the defaulting debt will need to somehow find more money to save their banks that are choking on their own countries exploding debt.  Nice huh?

Third, ISDA would rule in favor of a non-default because it keeps the laughable game going for just a bit longer.  This is the irony of the entire mess in my opinion.  Everyone at the table knows that there is no fix here, it is just a concerted effort to keep the plates spinning as long as possible despite the fact that any extension of the duration of this mess just makes the next mess worse.  It is all a sham.

WHAT IS THE IMPACT HERE?
Well, if you disrupt the natural forces of the market where some win and some lose by ruling that losing isn't losing (no default) you create a situation where all buyers repudiate the offerings in the Eurozone.  Can we substantiate this?  Of course, let's look at Italian bond yields since the heist occurred.


Next like all government interference, we'll see some kind of anti-market forces that try to hold rates down and keep prices up, further distorting the market pricing mechanism.  Take a look at the following  Zerohedge article for information on this escalation.  Italy Calls ECB's Bluff.  By the way, as I'm proof reading my post that I've been working on for a few days, we see that the yield continues to rise another 15 bps or so to 6.65%.  This is not the sign of anything healthy, the Italian crisis is now underway.

WHAT DOES IT ALL MEAN?
So, where we are at today is that the Eurozone, ECB, IMF, G20 solution achieved in the last week along with the outright rigging of the system by ISDA has ushered us one level lower in the death spiral of the Eurozone collapse.  If you had been a buyer of bonds and had excellent risk management techniques by buying protection to offload risk, you no longer have that capability and you actually have a ton of risk on your books.  Essentially, you are very pissed off and scared to death!  Another way of saying it is that you are no longer a buyer of these bonds at any cost.  As a result, the ECB is having to step in an buy these bonds at issuance to keep Italy from blowing sky high, although the damage has been done.

As we can see from Felix Salmon's article, the ECB intervention did nothing to save MF Global, and I suspect that we'll see more of these things as we find that hedgies and even banks that were holders of sovereign bonds are really hurting (Jefferies anyone?) as they don't have the protection they thought they had.  The MF Global bankruptcy and theft and mis-management ranks within the top 10 in terms of size of all bankruptcies.  How can this happen?  How can their be rumors of hundreds of millions of client money missing?  How can this have occurred in this age of significant oversight and regulatory control?  Clearly we've learned nothing and clearly the ECB, Eurozone, or US government are not in a position to save anyone or have any idea how to do it.  The only goal in all of these actions is to extend the time before the implosion finally happens in all of its nastiness.  Get ready, it is still coming.

GOATMUG

Goatmug is an investor that cares about you and your family. Goatmug's Blog - Financial Perspectives From The Mountain Top is a collection of thoughts on our economy and how it impacts the lives of investors and average people. While several specific investments are named in many of his posts, these articles are simply invitations for you to do your own research and reference to these securities does not constitute financial advice. Your situation is complex and unique and you should seek professional assistance with your trading and investing. Please visit Goatmug and share your comments at http://www.goatmug.blogspot.com/


Saturday, December 4, 2010

EUROPE ALL FIXED? MAYBE NOT - EURIBOR

AMAZON.COM - Just a quick note from our sponsors!  If you are looking to do some internet shopping, I've discovered this place called Amazon.  On the top right hand side of the blog you'll see a search box for Amazon.com.  If you do decide to buy something from Amazon.com please search through our blog and then make your purchase directly on their site.  After more than a year of blogging we are up to $8 in revenues and we're excited to see that awesome trend continue!  (Seriously, search for something!)

EURIBOR RATES
Judging by how the market has been trading this first week of December you might have the idea that everything in the world is great and getting even better.  Ireland seems to have been saved, remember Greece, it too must be fixed.  There can't be any issues with Portugal, Spain, or Italy can there? 

I wanted to share a quick picture of what Euribor trading thinks of the rally and the job of saving the world that the IMF, ECB, and of course the FED did last week.


6 MONTH EURIBOR
First, let's look at 6 month Euribor.  We seem to have come off just a hair from stress levels.  I'll continue to watch the "recovery"


3 MONTH EURIBOR
Next, here is a view of 3 month Euribor.  I am not overlooking the impact that year-end funding decisions have here.  While we are already in December it becomes increasingly tough for firms and banks to borrow over the holiday period.  As a moneymarket trader in my first years on the desk, this was the scariest time to be in a position to be without funding for the firm.  Most companies that needed funding and didn't already have it sewn up in the last weeks of the year were going to get punished as buyers of their risk would hold out for higher rates.  I don't think that the spike and recovery here is due to year end funding, but I'm sure there is some move up (slight) simply due to the time of year.


1 WEEK EURIBOR
Finally, we have a snapshot of 1 week Euribor.  Everything looks pretty good here, but take a look at what happened over the last 2 days of the snapshot.  That doesn't indicate to me that everyone is comfortable that a resolution in Europe is complete.


CDS - SOVEREIGN RISK
Last as I check in on sovereign debt CDS at Markit we see that Friday's trading in CDS demonstrated that things were getting better.  For 5 Yr CDS protection we see the following (which were all improvements).

Greece - 922
Portugal - 449
Spain - 294

While all of these have shown a tightening of spreads in the last week, they all are wider on a monthly basis

Be careful!

GOATMUG

Tuesday, November 16, 2010

UNCLE BEN'S SAVIOR / A BURNING EUROPE -

EUROPEAN COLLAPSE?  EVERY COUNTRY FOR THEMSELVES!
I'm too entrenched in work to write a long passage here, so I thought it might be best simply to reference a post by Mish here that highlights the big trouble in little Europe.  As you know, Mish is one of my favorites and I read his stuff almost daily.  Please read - EU President Proclaims "Survival Crisis"; Everyone Wants a Bailout of Ireland Except Ireland; Austria tells Greece to Get Stuffed; Currency Ping-Pong

As I mentioned in the November update, the only thing that could have derailed QEII was the one thing that I'd been watching daily, European Euribor Funding Rates and Sovereign Debt CDS (Credit Default Swaps).  In beginning of the month post titled "November Update - Man Do I Feel Richer" I highlighted that all emerging markets anything and all commodities were much higher and I felt great.  I continued in the trading section to say that this would continue UNLESS...
 "If these continue to blow out this could derail the heroin induced rally the Fed has us on, just like what happened in April of this year."

JUST LIKE THE FIRST TIME
And so just like in April, we tested the highs of the year only to sink back quite quickly in a sea of fear that Europe would implode and the mess that is the financial community might spread its contagion around the world again.

So, I continue to watch those Euribor spreads like a hawk and it seems as though those are stabilizing and I'm watching CDS spreads as well.  While I said that this pullback was healthy and expected we need to watch the stories about Greece and Ireland.  I'm not doubting that they will come to some bailout - like they do every other time.  They must, or else the games cannot continue for everyone and every central bank.  So, my real outlook is that  I do believe that it is going to continue two or three more days which could be ugly, but theirs always a sticksave in the weekend isn't there?  As soon as we hear more people telling us that this really is the end and then we'll find our white knight (Uncle Ben and his boys and perhaps Jean Claude Trichet too?) to save us all.

I have trimmed my short term trading accounts but am not short here and don't want to get sucked into the idea that we'll see a complete meltdown. 

THE FIDDLER STRIKES AGAIN
I am seeing lots of weird stuff going on in the market and normal relationships are breaking down so it is always important to continue to be vigilant.  Oh yes, and right on cue when the dollar looked like it was about to be totally trashed and thrown away in a dumpster what should be find?  That's right, a European collapse!  Perfect timing allows the US to see some upward movement of the US dollar and gain some technical traction.  The European financial fires are music to a fiddling Uncle Ben.

Be careful!
GOATMUG


Tuesday, November 9, 2010

NOVEMBER UPDATE - MAN DO I FEEL RICHER!

IN FED LANGUAGE, PRICE STABILITY MEANS A BLOW OFF TOP

Call it QE II, monetization, printing, or the precursor to QE III, call it what you like but just don't fight it.  The FED's overt action to inflate asset prices at any cost have trumped all market fundamentals and created an asset price surge into the stratosphere.  Chairman Bernanke states that he wants price stability, yet his definition of price stability must not include a normal ebb and flow, it must only include a moonshot ramp job.  I would contend that we have anything but price stability at the current moment.

I've captured a few sentences from Fed Governor Mishkin in a 2007 speech.  In this message he highlights the dual mandate that the Federal Reserve has in its role. 

"According to this legislation, the Federal Reserve's mandate is "to promote effectively the goals of maximum employment, stable prices, and moderate long-term interest rates." Because long-term interest rates can remain low only in a stable macroeconomic environment, these goals are often referred to as the dual mandate; that is, the Federal Reserve seeks to promote the two coequal objectives of maximum employment and price stability. In the remainder of my remarks today, I will describe how these two objectives are consistent with our ultimate purpose of fostering economic prosperity and social welfare. I will then talk about some important practical challenges in implementing these goals. "

Let's examine how we are doing with those goals?  Maximum employment --- QEII and low interest rates have done nothing for this goal.  Stable prices?  We'll dig more into this, but this is absolutely false and prices are getting more out of whack.  How about moderate long-term interest rates?  I'm going to suggest that this is also missing the mark.  QEII is about reducing interest rates so the US can meet its debt obligations and keep the illusion of US solvency intact.  If and when there is a rationalization to normal interest rates there will be no such thing as moderating interest rates.  Strike three in my opinion on the mandates and target goals of the Federal Reserve.

What's the purpose of all the QE?  You must know that Chairman Bernanke and former Chairman Alan Greenspan believe that greater stock prices will lead consumers to buy more and borrow more as the "wealth effect" creates in their mind a sense of having more money.  The notion that asset prices are increasing caused many in the early 2000's to lose all sense of rational expectations and believe that housing prices would always go up, that houses were the equivalent of ATM machines, that living off of one's credit cards is ok, and that all people deserve and are capable of being rich.  While the mistakes and poor thinking in the 2000's were quite real, I am optimistic that Amerikans have learned some lessons and won't fall for the old asset price wealth effect trick again.  Perhaps I'm naive, but I think many are now focused on living within their means and paying off debt, not incurring new and larger obligations.

September and October have provided almost all markets with out sized gains and have posted record results.  Clearly the economic fundamentals must reinforce and justify the rocket launch right?  Let's dig in and see where we are at.


RAILS - http://railfax.transmatch.com/  and http://www.aar.org/NewsAndEvents/~/media/aar/railtimeindicators/2010-11-rti.ashx


Total Rail Traffic continues to outpace 2009 levels for the current week.  We are about 10% higher than those levels, yet are still down 4.2% from 2008 numbers.


RECESSION INDICATORS
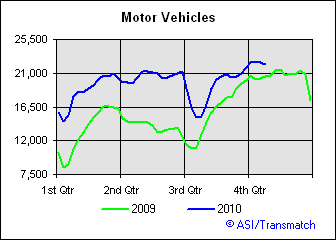
Waste and Scrap shipments are on par with last years levels.  These shipments don't give us a clear indication of strength or weakness.  Motor vehicle shipments are greater than 2009's dismal levels, but this should give us reason to pause and temper our elation.


As I mentioned an earlier post this week, the Food Stamps Program continues to see greater and greater participation.  The SNAP data continues to highlight how bad things have been on mainstreet.  More families are drawing on the resources of the federal government and taxpayer for their food needs.


Moody's MIT Transaction Report - Commercial Real Estate
The CPPI continues to decline and show an erosion of value in the national commercial property price index.  The figures released for August show another 3.3% decline in values in actual transactions.


HOME PRICE INFORMATION / LEADING INDICATORS - ECRI - http://www.businesscycle.com/resources/
The ECRI data on home prices continues to show no improvement in this critical area of the economy.  Real prices continue to reel and go lower through the August data release while leading indicators suggest that the pricing is simply flat.


MONSTER EMPLOYMENT INDEX REPORT - http://about-monster.com/employment-index
Jobs reports last week were surprisingly good and we see improvements in the weekly data.  Unfortunately we are not seeing an improvement in the unemployment rate at more workers that just gave up are now coming back in search of job opportunities.  Our unemployment rate is still at 9.6% and is quite sticky at that level.
Despite the good release, the Monster.com Employment Index dropped from a level of 138 to 136 in October.  Why new job listings on the web would decline here is actually interesting.  This is a really good report to watch and get some indication of where we are going. 

On a separate note, Monster reported excellent earnings a couple of weeks ago.  I should have been on this as an investment possibility as the huge surge in the index would and should have been a tip off to the potential rebound in earnings for the company.  I'll continue to keep that in mind as I track this and highlight it as a potential trade in the future.


6 MONTH EURIBOR - Euribor rates continue to climb.  Some of this increase is a result of the European nations holding firm and refusing to follow the stupid policies of our Federal Reserve.  The lack of "relative" stimulus provided in Europe is marked by higher interest rates.  Having said that, there are still real problems in Europe with countries like Ireland and Portugal, and don't forget our old friend Greece.

No matter what, it is unmistakable that there are "interesting" things going on in the last month as the 6 month Euribor rates have climbed about 15 bps or 10%.  This is an inexact gauge but it is an item I watch every day in an attempt to measure stress in the banking system worldwide.


CDS SPREADS -  http://www.markit.com/cds/cds-page.html


To continue on the thread that sovereign debt is still an issue, I wanted to include some data related to the CDS (Credit Default Swaps) pricing to offer protection against a default of one of these countries.  You must recall that earlier this year CDS prices exploded as the European debt crisis was unfolding again.  I am absolutely certain this will happen again just about the time when everyone forgets that these countries are really insolvent (like the US and every large bank).  For those that aren't accustom to looking at these, note that the spread is 992 which means that a person would pay 992 basis points (bps) for protection against a default in a specific bond issued by the Venezuelan government.  992 bps is 9.92% a year!  I personally never traded country specific CDS, but did do significant amounts of CDS in your investment grade corporate bond environment.  Back in the early 2000's we would write protection on names like General Mills and Kraft for around 40bps (for very short time frames (1 year).  While Venezuela is improving over the last week and month, Ireland, Spain, and Portugal CDS spreads are going nuts.  Increases of 25% are an indication of stress in the system!  DO NOT GO TO SLEEP ON THIS!  Remember April, when every thought we were going to keep going higher and then we hit this little debt crisis?  Can you say "DO OVER?"

Venezuela
Spread  992
Daily Change  28.55
Weekly Change -91.92
28 Day Change -24.08

Ireland 
Spread - 607
Daily Change  17.69
Weekly Change 109.17
28 Day Change  182.55

Spain
Spread 264
Daily Change  15.98
Weekly Change  39.83
28 Day Change  56.18

Portugal 
Spread   464
Daily Change  14.89
Weekly Change  70.65
28 Day Change  78.57


WLI DATA - FROM ECRI -  http://www.businesscycle.com/resources/Last week's WLI Data shows continued improvement in the leading indicators.  As I examine this data I find that since June 18th of this year the actual WLI data is showing a change of around 1% from that time.  At the same time though, the S and P 500 is up more than 6% from those levels.  It is clear that there might be improvement here in as shown by the WLI, but the market's rally may be ahead of itself.


COPPOCK TURN INDICATOR
The Coppock Turn Data continues to signal a turn south in the markets despite the exponential run in markets.  The turn indicator has been wrong for two months now, but since it is a lagging indicator we must expect that and use this as just another warning.  As usual I've tried to project levels in which it would actually signal a continuation of the positive trend, that level is at 12,300 on the Dow.  I don't put much weight on this indicator, but include it as another data point.


FINANCIAL CONDITIONS INDEX- http://www.bloomberg.com/apps/quote?ticker=BFCIUS:IND
As you all know, I like the Financial Conditions Index provided by Bloomberg because it is a composite of many fixed income and monetary (liquidity) measures.  The FCI is showing a value today of .15 which is once again over the critical 0 level.  This is an indication that there is an expansion in the economy, but probably more accurately there is a huge expansion in the amount of liquidity in markets.  We are nearing the  0.5 level we saw in April and this is going to either be a level of strong resistance coupled by the resurgence in a market correction, or it will give us an indication that the economy is truly recovering and going to be the basis for even greater levels in the stock and "asset" markets. 


BALTIC DRY GOODS INDEX - http://www.bloomberg.com/apps/quote?ticker=BDIY:IND
With the ever-increasing prices for copper and other commodities, one would think that spot rates for transporting these goods around the world would also be increasing.  In this case, that is actually not happening.  As I've posted many times, the BDI is subject to many issues other than simply that commodity prices are going higher.  First and foremost, I think the issue is that there is a ton of supply of ships available to move this cargo as shipping companies continued to order ships several years ago.  I have seen a few comments about purchasing some of the dry bulk shippers like DRYS.  Based on the chart I'm seeing, the thought of picking up a few shares might not be a bad one considering that there has been a recent breakout and it was confirmed with the move above $5.00 as I type.  I also like that the increase has come on increasing volume.  A very conservative trade could call for a stop to be placed at $4.90 and an upside target of $5.70.


DRYS CHART


USD INDEX - http://www.bloomberg.com/apps/quote?ticker=DXY:IND
The USD index continues its assault on lower levels despite 2 days in a row now of being up.  Since the May/June peak around $88, we've seen an almost uninterrupted dive to $76.  Imagine that, a 13% drop in the value of the dollar and a move up in the overall markets of around 16%!  Clearly the move higher in the markets is not due to improving economic fundamentals and a healthier environment.  The unsustainable recovery in index asset levels is purely a move derived from US dollar debasement.

The FED's announcement last week of the use of $600 Billion of newly minted QEII to "stabilize" our economy has essentially created an environment where everything simply goes up.  As the dollar goes down, asset prices in stocks, commodities, and everything else have simply risen to keep value somewhat constant.   And if you didn't believe that Bernanke and the FED were serious, there is the overt threat that there is even more liquidity behind the $600 Billion in case it is needed. 

While there is no proof that any of the QE will actually provide sustainable jobs or expansion in the economy, that doesn't mean that we won't have the facade of growth by way of ever increasing valuations of stocks.  Of course when you value those stocks in terms of foreign currencies or in hard assets you find that we are getting nowhere.

The area we are in is pretty critical and the $76.00 level must hold or else we will see a real fall in the USD and a tremendous surge (even greater than we've seen) in gold and silver and other anti-US currencies.  As stated previously, the gold and silver trades are now more than just commodities, they are trading as their own safe haven currencies and have taken on a life of their own.  Yesterday the dollar was actually up and we saw silver go nuts.  It is on days like these that I wish there was an easy and quick way to sell my physical silver as we've seen an almost 20% move in silver in two or three days.  I've heard several stories as to what is going on with these moves from a massive short squeeze to the filing of inquiries and court actions against JPM for silver market manipulation.  No matter what the cause, it is almost enough for me to want to exit.  I simply haven't due to the trouble associated with packing it up and sending it out for sale.  (Anyone want to buy some silver?)


NOVEMBER TRADING UPDATE
As much as the broader economy's recovery is still in doubt for me, there is little doubt that the FED is acting to not only buoy this market but to attach a rocket pack to its back and propel it to the loftiest levels.  The policies that are being executed are making it impossible for one to remain in less risky assets like money markets and also makes one very cautious to hold on to other fixed income type holdings as the specter of run away pricing erosion becomes more real.  What I mean here is that despite the notion that I still believe that we do not have inflation, there is rampant asset speculation in all the old standbys.  Oil, copper, wheat and grains, sugar, coffee, cotton, and more all are going parabolic.  I will say it again that this doesn't mean we have inflation, but it does mean that we have speculation like we did in June/July of 2008 where oil reached $147 a barrel.  No one can suggest that that price in oil was caused by actual demand, but it was caused by loose monetary policies that brought our economy to its knees.  It blows me away that we can have a FED that will sit idly by and allow it to happen again.  What kind of recovery will we have if my $100 a barrel target for oil is hit?

Despite my protests, the FED has promised QEII and will promise more of QEIII as the second version fails.  As a result our old trades are extremely profitable and are still ones that I highlight as winners.  We need to remain in commodities like DBA, DBC, JJG, SLV, GLD, and more.  We need to continue to trust in emerging markets for the reason that they are ACTUALLY growing at a pace well beyond the US's 2% AND are investments that are outside of the USD.  Countries like Chile,  Singapore, Malaysia, and Brazil have been my favorites.  They have been winners for me for sometime and that trend has not been stopped.  While there is every temptation to harvest gains, the real question needs to be....."And go where?" 

As we have discussed, the potential canary in the coal mine here is the stress in the European countries as measured by Euribor and also by the sovereign debt CDS that I pictured above.  If these continue to blow out this could derail the heroin induced rally the Fed has us on, just like what happened in April of this year.  I don't want to get too excited about any drop in the market though because we have rallied so much in such a little time with NO pullback.  We must expect some drop simply to digest the recent gains.  WATCH THESE CDS AND WATCH THE EURIBOR RATES THEY WILL BE THE INDICATION THAT SANITY IS RETURNING TO THE MARKETS!

Given the tsunami of liquidity and threats of more liquidity we will continue to see more of the same for the next month as the FED continues to debase and devalue our currency in an attempt to make us all feel richer.   Man, do I feel richer, don't you?

Be Careful!
GOATMUG


Tuesday, May 18, 2010

WOPR JUST TOOK US TO DEFCON 4 -

Remember the computer from the movie War Games --- the WOPR?  Remember how it just wanted to play a game?  In playing the game the computer began automatically ratcheting up the security protocol for the US and it perceived the game was real and couldn't differentiate between the two.  Well WOPR just kicked up the alarms a few notches!

If you weren't at Defcon 4 or 5 you better be now.  The Germans made some unilateral decisions that might be the sudden catalyst for upsetting the finely tuned ponzi scheme that all central banks have been playing for the last few decades, but really moving all their chips in over the last 14 months.

The decisions made by the Germans attempt to do a number of nutty things but they essentially are trying to ban speculation of government bonds.  They also attempt to ban shorting of their top 10 financial institutions and insurers and ban on naked CDS.

HAVE THE GOVERNMENTS LEARNED NOTHING?  It was the shorts that have uncovered and discerned all of the lies in the credit and equity markets.  It is the shorts that continue to uproot the misdirection and over leverage in banking and government debt.  It is the shorts that provide liquidity and fodder for bulls when the markets turn around.  As we witnessed when outlawing shorts is implemented there is typically a brief move upward followed by a complete meltdown.

When word of the ECB and IMF bailout surfaced last Monday word hit the street that German citizens rushed (not walk) to gold and silver dealers and quickly bought out domestic supplies.  The Germans have the strongest economy in Europe and if there was an actual referendum on whether to bail out the Greeks or other nations it would certainly fail.  And this point is crucial.  Have you noticed that all participants in this world crisis are unwilling (citizens that is).  Did you get a proxy statement in the mail regarding your desire to have the United States provide $50 Billion to the IMF (we are 17% of the IMF funding)?  No, your dollars are being spent and national sovereignty and representative government is being usurped.  Congress appropriates funds not some IMF, the FED, or the Treasury!  You are witnessing the disconnect between the ruling class and those that are being ruled.  In the US we like to claim that we are free, but clearly use of our tax dollars to support an island in Southern Europe does not benefit us nor is there a likelihood of repayment.

What would cause the Germans to buy gold?  I think those citizens know that the Euro cannot last given the pressures that are mounting.  Several nasty things can happen as a result of the one-sided decisions made by the Merkel led government in Germany.

First, Germany's sovereign debt may drop significantly in value as traders and portfolio managers attempt to exit positions related to their country debt.  Look for US Treasuries to go higher in value and yields to continue to drop.
We'll see European stocks drop and also we'll ultimately see German banks drop significantly.  Any rational investor must be asking what the German government regulators are seeing on German balance sheets and what is causing them to strike out at short sellers.  Look for these very institutions that are being protected to get hammered as people exit positions in fear.

Of course the dollar will rise.  Large banks in the US will get hit although larger US firms that pay dividends may go down less as there will also be a flight to safety.  Think utilities and telecom here.

Global contagion is a real possibility here.  In the 30's the 2nd collapse in 1934 was caused by the failure of a German bank - by the way, that drop in the stock market lasted for a couple of years and amounted to an almost 70% drop.  In the depression there was also a move by world governments to create protectionist schemes and make decisions that impacted other nations unilaterally.  (Sound familiar?)

I'll post more, but you've been warned and I hope as usual that I'm just being alarmist.

GOATMUG

Tuesday, April 6, 2010

APRIL UPDATE


APRIL SHOWERS - WHAT WILL SPRING UP?

RAIL TRAFFIC -

Total rail traffic continues to improve from the collapse that occurred in the first quarter of 2009. This improvement suggests that the economy is getting back to normal - even if it is a "new normal".


Continued improvements in lumber and crushed stone are signaling that commercial real estate development may be coming off of its death bed. I am not sure that I am going to ring the bell and say that the commercial real estate sector is fixed, but it appears that someone is crazy enough to begin purchasing some of these components and we need to be looking for this activity to translate into market health (and no, I don't mean stock prices for commercial real estate and builders to go higher --- since they have already run). I'm actually looking at this data to at least validate some of the market's move. If this stalls out, then we know that perhaps there are perils to be navigated in this sector still.


Shipping tonnage for all sectors have now outpaced last years rates and now are all positive. The greatest increase has been in metals compared with last year while coal shipments are the least best improved at +3.2% from last year's period.


KSU continues to show get improvements in shipping and has been the one we've followed for some time. Clearly we sold too soon, however I'd rather do that than lose hard earned gains. I will not cover that trade again till it comes back in line with previous levels. I feel like there are better risk/reward set ups to examine.

US DOLLAR


The march higher since November of 2009 seems to have abated some as the USD has taken a break. Perhaps much of the "break" here is that we are again pleased to hear that the Greece situation (Grease Fire) has been put out and a solution to their overspending and obstruction of truth has been solved for the moment. Since we seem close (maybe this time?) the dollar has moved south in relation to its rivals and has led to the resurgence in the stock market and especially in the emerging markets and commodities markets. Of course this dollar weakness put a halt to my celebrations in my YCS trade (double short the yen), however I still have that trade on since it has not penetrated my $20.50 stop.


We'll discuss the dollar more as we wrap things up, but it hasn't escaped me that this dollar fall is part of a well orchestrated and choreographed dance. Think of a rhythm and vibration rather than a waterfall drop into an abyss.


FINANCIAL CONDITIONS INDEX -


Fed liquidity continues to be available and therefore the FCI has signaled an end to the recession and a beginning to an expansion. This indicator is one that continues to make we believe that we are "all systems go" for a move higher through the end of April and perhaps mid to late May. The FCI is flashing all clear.


BALTIC DRY GOODS INDEX-

Just to sprinkle in some reality, the baltic dry goods index marched higher in mid March and then had a lid slammed shut on it. We'll continue to monitor this spot shipping pricing indicator, but we needed to see a push through into the high 3000's and 4000's for me to take real notice. The actual shipping companies had rallied strongly in mid Feb through March, but have retreated as well. In fact, my quick take is that several of the shippers in this space deserve to be shorted, as they have rallied right into pretty stiff resistance.


I am hearing that commodity prices are rising, however I also hear that actual demand is not. Orders requiring spot shipping prices are simply made to fill the void of diminished inventories and suppliers and manufacturers are not moving to follow through on a great inventory rebuild because the volume of orders on the horizon are just not there. As a production manager wouldn't you be slow to add an inventory of raw materials that may sit idle in the face of rising prices that you assume are not based on true orders fundamentals?


EMPLOYMENT -

March Unemployment figures officially still show we are at a 9.7% unemployment rate. This actually may rise as people get hired causing those seekers to that gave up to re-enter the workforce.


I haven't written much about employment lately, but I am hearing some positive stories from friends through the country. Let me first highlight the Monster Employment Index for March. I've never referenced this item, but figured that I'd put it in. The Monster Employment Index is showing continued increases in job listings online, especially when compared to the easy comps of one year ago. Some would argue that the rate of change is not rapidly increasing from last month, however it is positive. I'm more inclined to be positive because this jives with what I am seeing and hearing from folks looking for work. They are saying that there are beginning to be more opportunities. These guys are not reporting that they have actually landed a new gig, but they are suggesting that it is close and opportunities exist where none did previously.


- Quote from the Monster Employment Index Summary -
During March, online job availability rose in 12 of the Index’s 20 industry sectors and in
13 of the 23 occupational categories monitored.


ECONOMIC SENTIMENT -


The Dow Jones Economic Sentiment numbers were released a week or so ago and we find that again we are seeing slight improvement in what the masses are hearing in news stories about the economy. I think this is a pretty funny study simply because it measures how many positive news stories are being fed to readers of the top 15 major newspapers.


I cannot cut and paste and reference the actual graphic for the study, but like everything March of 2009 was low and there has been a pretty steady crawl up and to the right since that time. http://solutions.dowjones.com/economicsentimentindicator/


I will be interested to see how CFO sentiment improves to validate this study. It won't be out for several months, but I'll add it when it is posted.


TRADING INDICATORS AND SENTIMENT
Well, as you might have guess it, almost all of my trading gauges and indicators are screaming that this market's rise is overdone. I will make reference to a couple of items to demonstrate just how cautious we should be in the short run as investors seem to have become complacent and expectant that markets only go up. While this has been true for the last year with a few brief corrections, we all know that this market will continue to go higher till it doesn't. And when it doesn't, it will be pretty nasty.


Guy Lerner at http://www.thetechnicaltake.com/ has again put his charts into action and demonstrated that hedge funds and individual investors are "all in" and have bought with abandon. The "smart money" is neutral or slightly bearish meaning that you have two opposing forces in these trades. Typically, we see the retail investor (Mom and Pop---us) on the losing end of this trade. Guy has some great content and a really cheap subscription for trying to time the market in short time frames (1 to 2 days trades). I constantly use his work and suggest you read him daily.


I've also received permission to copy and link to a new site that includes a valuable indicator of market breadth. Lee Franzen at http://www.growthstock.com/ Lee has a subscription service (I don't personally subscribe to this one), as well, but he does provide some great tools that are updated daily for free.


Specifically, Lee provides an indicator similar to the T2107 indicator that is available if you are a subscriber to Telecharts. The indicator provides information about how many stocks in the S&P 500 are trading over their 40 day moving average. Typically we are looking for extreme values in this measure to indicate that we are over-valued or "overbought". Click on the image below and at the bottom right hand corner you'll see that we are clearly at extremes and many stocks are now above their 40 day moving average. Now just like everything does that mean that the never ending rally will conclude tomorrow? No, but it is just another signal that we may be topping. Thank you Lee for allowing me to reference your great site. Please check out his subscriber service to and let me know if you like it (I have no affiliation or compensation agreements with Lee, he is generous enough to share his hard work with us here). http://www.growthstock.com/Market_Breadth.html

(For the next few pieces of information, please bear with me - I don't have permission to copy these charts, but they are so simple and clear that they are worth the extra time necessary to click. I will see what I can do to get them to allow me to post their work here.)

INTEREST RATES
Interest rates are rising. Check out this link - http://www.multpl.com/interest-rate/
We are going to witness increasing rates if all things continue as they have. Given that we are going to see interest rates move higher we must ask ourselves the question - "Can we really tolerate a move higher in rates which will cause a slow down in the recovery of the economy and housing?" The answer to this question is that we can only endure it if we are willing to trash the dollar to get there. Guess what - the Fed is willing to trash the dollar to get there! Everyone take a deep breath and sigh of relief!
This statement ultimately goes to what I was mentioning about the moves of the dollar. I perceive the move up in the dollar almost as though it was planned and rehearsed. The Fed wants to devalue the dollar but cannot make it look like a beeline downward. They must generate a zig and a zag a vibration or oscillation north and south to reduce the value of the outstanding debt and constantly newly issued debt. This is their only hope to move beyond what we have endured.
Of course you know the trades that will succeed in this environment if all goes as planned --- NON US ASSETS AND COMMODITY BASED ASSETS --- ALTOGETHER NOW!
EMPLOYMENT CHART - Here is a graphical demonstration of what we've been saying --- hmmmm all better?
Can these unemployed tolerate higher interest rates or mortgage resets or increasing credit card minimums? No.

SUMMARY - PUT IT ALTOGETHER
Ok, so how does this all come together? The deal is that we have two powerful forces at work that are attacking one another. We have the FED in one side of the ring and they are flexing all of their weapons at this moment and in fact might even becoming confident and hurling a few insults at their opponent.
In the other corner of the ring we have Mr. Deflation (Mr. Mathematical Reality) and he is feeling a bit beat up. In fact, Mr. Deflation believes that the Fed is cheating and even probably has a horseshoe in his glove like those old cartoons.
The Fed (and his buddies) has used all of its tools to win this epic melee. The Fed and Treasury have devalued the dollar, printed trillions, revoked all semblance of accounting rules, purchased MBS and treasuries in the open market to control interest rates, and probably even purchased the sovereign debt of troubled countries or at least entered into swap agreements that allowed for hiding of distressed liquidity needs.
Mr. Deflation has also battled well. He has reduced the value of almost every home in the United States, he has caused record bankruptcies, he has caused the consumer to briefly come to their senses and live within their financial means, he has cause US citizens with jobs and money to actually pay down debt, and cause a reduction in home sales and car sales that required "CASH FOR CLUNKERS AND CASH FOR HOUSES" to be rolled out to salvage what was left of two industries.
So who wins? The simple answer is I still don't know. The FED is resilient and in the short run has access to powerful weapons and Ben Bernanke is not afraid to use them. In fact, he knows he better use them because in his mind there is no losing. Losing is similar to death and he won't have that!
Picture the scene in the Godfather where the gangster screams "Say hello to my little friend".... Well Benanke has a little friend too and his little friend is the printing press. The Fed is absolutely convinced that deflation is death and they will destroy the dollar to avoid the gripping destruction that Japan has faced for two decades.
Ultimately, in the long run, I believe that Mr. Deflation wins. Just ask our Japanese who is tougher - a central bank that protects corrupt bankers or a deflationary force that requires justice and a honest evaluation of how much bad debt a country can absorb and still grow.
I was asked what I thought the catalyst for Mr. Deflation winning or at least beginning to steal some rounds recently. The answer is that it could be several things at once. The synergy of rising interest rates, tougher lending standards that shift downward the demand for housing, more sovereign debt issues (think Spain, Portugal, and Ireland---don't forget Dubai), crushing debt and US deficits, or even a collapse of a bubble in China or other emerging market economy. Remember ALL countries are trying to recreate the fantasy land of 2006 & 2007 and it isn't just the FED that has a printing press. Ultimately most countries are also trying to devalue their currencies.
I ask you. What specifically has changed in the last 1 year? Have banks written off all of their debt? Have they evicted all of those owners that are in foreclosure? Have banks written off their worthless HELOC balances? Have we begun to enforce real accounting principles? Have we regulated CDS as insurance? Have we received back all of our investments in AIG and Citibank and Fannie Mae and Freddie Mac? Have we returned the last two to solvency or are they simply bankrolling terrible mortgages that will never be repaid?

My guess is that nothing has really changed beside the upward recovery of the stock market. At some point the smart money will decide to go short the market and they'll pull the rug out from under Mom and Pop and leave them utterly burned for the 3rd time this decade. Unfortunately this time their assets will probably be destroyed in the process.
Does this mean that the party is over? No - in fact for this entire year I suggested that this rally may continue through May. We need to harvest gains in the portfolio and position ourselves in sectors and industries that have improving fundamentals that have lagged the others. The idea is that these will not correct as much and probably gain as investors search for value.
I do not have a specific trade to discuss this month. While I do like a few charts I will wait for break outs that are significantly above their resistance if we go higher to confirm the move. I don't like the risk/reward here even though many fundamental factors are showing continued improvements.
BE VERY CAREFUL - friends I speak with have almost forgotten the word risk and that can only mean that we are due for a correction. This may be a great opportunity to add as we pull back.


GOATMUG