Wednesday, February 16, 2011

PART II - KYLE BASS - THE EUROPEAN EXPERIMENT

Part II of the interview includes Kyle's perspective on the European economies and why the entire experiment is going to fall apart.  There are some funny stories about Greece and the fraud there.


Enjoy

GOATMUG

PART III - KYLE BASS ON CNBC - MUNI BLOW UP?

In part 3 of the strategy session, CNBC interviewers ask Kyle about his views on municipal bonds and the comments made by Meridith Whitney about the impending collapse of many municipalities.


I hope you took the time to watch parts 1 and 2 at least.  Kyle is very patient and willing to let math work on his side.  Hopefully you'll take his lead and invest accordingly.

GOATMUG

Tuesday, February 15, 2011

COUNTDOWN TO EXTINCTION / KYLE BASS WRITES THE SYMPHONY OF DESTRUCTION

Goatmug often writes solely about economic and trading things in an attempt to warn readers of the disparity between feelings and reality.  In fact for the last eighteen months (since August 2009), the disconnect between feelings and reality have led us to actually invest heavily in commodities and emerging markets despite our longer term fears although we've maintained a careful eye on the "fundamental picture" of reality.  We've essentially had to hold our nose and deploy dollars, despite the fact that we know how it will actually all end sometime in the future and attempt to target areas that would provide enhanced returns.

As I look back, I recall feeling this way in 1999 as an investing novice witnessing worthless companies become overnight sensations.  I felt deep concern in October, November, and December of 2007 when I asked many of my friends to abandon the markets because I sensed that carnage would soon follow.  Now, I still have real hesitation about the state of reality and want all of us to be on alert for a change in the posture and perceived health of the market.  Over the last couple of weeks the stock markets have slowed a bit and have not pushed significantly higher.  Perhaps this is just the buyers taking a breather?  As I have laid out in the 2011 Outlook, I did anticipated a drawdown of 3%-5% early in the year that would allow the markets to reach higher levels inimid April or May.  Guess what?  We haven't really seen that pullback as of this writing.  Timing is everything so we simply need to watch for new cracks and signs of weakness.

I was sharing with a friend today that we must also be on the look out for the end of QEII.  My thoughts for a significant pullback in late April to May has been predicated on the idea that large institutional investors will anticipate the end of QEII in June of 2011 and therefore attempt to get out in front of a draining of the liquidity swamp.  At that time we may see all assets fall and the USD and treasuries actually gain.  I do not believe that these institutions will wait till June to make their moves to see if QE II will be extended or QEIII spawned.

On a longer term time frame (before 2015) there are other pot holes to be aware of.  In the past I have mentioned one of my favorite investors, Kyle Bass of Hayman Capital Management, L.P as one of the smartest guys in the room that was sounding the alarm to the impending MBS and real estate collapse years before it came to fruition.  Kyle made more than $1 Billion betting against the entire industry in 2007 and 2008.  Kyle was featured in CNBC's documentary House of Cards.  Please find my previous posts here - Kyle Bass Part I- Why the Fed is Trapped and also House of Cards .  Kyle is sounding his alarms again and going deeper into his thesis that Japan's massive debt will be one of the first sovereign collapses that well see.  In his article to clients called "The Cognitive Dissonance Of It All", Kyle lays out his firm's view that Japan will not be able to sustain their high debt levels and low interest rates.  So far the country has managed to survive because they have had a nation of savers, but because most of their population is now nearing retirement, they face the mathematical impossibility of keeping their pozni scheme going. 

http://www.zerohedge.com/sites/default/files/Kyle%20Bass%20Feb%2014.pdf

You must read this article!  One of the awesome quotes from his letter is captured below -

"One last point about Japan that is more psychological than quantitative: there is an interesting psychological
parallel between JGBs and US housing. In the last 20 years, Japanese stocks have dropped 75%, Japanese real
estate has declined 70% (with high‐end real estate dropping 50% in the last two years), and nominal GDP is
exactly where it was 20 years ago. What one asset has never hurt the buyer? What one asset has earned a 20‐
year pro‐cyclical, ‘Pavlovian’ response associated with safety and even more safety? The buyers and owners of
JGBs have never lost money in the purchase of these instruments as their interest rates have done nothing but
fall for the better part of the last 2 decades. It is fascinating to see an instrument/asset be viewed as one of the
safest in the world (10‐yr JGB cash rates are currently 1.21%) at a period of time in which the credit
fundamentals have never been riskier. "

What Kyle is focusing on is exactly the type of thought that ripped the financial worlds to shreds during 2003-2007.  Kyle is pointing out that the Japanese Yen and the Japanese Bond is essentially priced to as a risk free asset, or said another way, always to be considered safe money.  Remember real estate?  Remember how all of the securitized deals and tranches of MBS were modeled on the assumption that housing values always would increase?  Remember how pervasive the notion that real estate was easy and riskless became?  Do you remember shows like Flip This House?  Remember your neighbor telling you he was going to start buying houses and telling you there was no way to lose money?  Essentially this is the mentality of investors in JGBs (Japanese government bonds - many of which have been Japanese nationals).  What happens when those Japanese nationals begin selling JGBs to fund their retirement?  What happens when those holders start to lose money on their bond holdings? 

What is beautiful about Kyle's strategy is that he doesn't need a total collapse of Japan to make huge sums of money for his fund or his firm.  Kyle simply needs the world to wake up and realize that there is a real risk that Japanese bond interest rates could go significantly higher, creating big losses for holders of Japanese debt.  I hate to say it, but it goes back to the theme I always talk about, this is about mis-pricing of the cost of credit.  Do you really think buying Japanese bonds at 1% or 1.5% for 10 years is a good deal?  Who is the world would do that?  This is the bet that Kyle is making.  Now a lot of things will go wrong when Kyle's investment bets (gains) are realized, as this will really lead to a systematic collapse of many other institutions and ponzi schemes. 

In closing, many of you may not know this, but Goatmug grew up a rabid heavy metal fan.  The Goat played a mean guitar and often dreamed of being on stage in front of thousands while shredding some hard core riffs on his 6-string axe.  Kyle's note reminded me of one of my favorite Megadeth tunes on the album Countdown to Extinction, the song's name was Symphony of Destruction.  Kyle has composed the symphony, the orchestra is assembling, it won't be long till the destruction is played out in real life on the financial stage.


Enjoy one of my favorites.

GOATMUG

Wednesday, February 9, 2011

FEBRUARY MACRO UPDATE - RECOVERY IN ASSET PRICE ONLY?

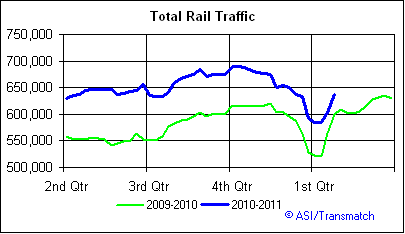
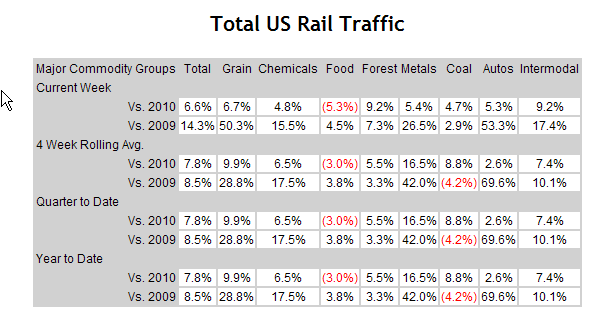
RAILS - http://railfax.transmatch.com/
Rails continue their march higher in terms of their increases in shipments compared to 2010 and 2009, with the exception of food.  Interesting decrease here, but as with all economic statistics that underperform we'll just blame the weather.  I recall my days as a Financial Analyst doing budgets for a big company where I simply used "timing differences" as my excuse for variances I simply had no idea why they were off.  I think "weather" is just like a timing difference.
TOTAL RAILS
We saw a season dip over the last month and now we are back into the ramp up stage.  It is important to have seen that we didn't cross below the 2010 levels here.

AUTOS
Motor vehicle shipments continue to be of concern as we just are increasing the shipments like we should given the super recovery that we have been promised.  Ford's disappointing report over the last week was essentially tipped by watching the rail shipping data below.  It won't be hard to imagine that GM comes out with numbers that are quite as good either.  Have you noticed that GM hasn't been able to exceed that $39 mark we highlighted several weeks ago?


RAILS / SCRAP TONNAGE
Scrap shipments continue to go along the trend line from last year.  Essentially the data here, with autos, and a few other items we'll review shows that this is a "recovery-less recovery" (yes, Goatmug owns the trademark on that!).


KSU - I've captured a few snapshots of individual rail tonnage for you.  All seem pretty similar, but the hope is to find the weak one of the bunch.  Let's see if we can find it.


NORFOLK SOUTHERN -
Looks actually a bit better than KSU.


CANADIAN PACIFIC - Uh oh, one of these pledges is not like the others.  (Remember, stock performance is all about expectations.  I would contend that that dip below 2010 levels may not be a positive.  I have looked at CP's chart though and it is pretty impressive.)


SCRAP COMPOSITE PRICE INDEX -
http://www.scrap.net/cgi-bin/composite_prices.cgi?id=100000&num=5
Scrap prices were Alan Greenspan's favorite macro-indicator, but I'm wondering if all macro-indicators are worthless in this asset price melt up and dollar meltdown environment.  This beautiful chart just continues to go up and to the right.


AVERAGE PRICE - HOME SALES - http://www.realtor.org/research/research/ehsdata
December home prices were released and we continue to see real estate decline.  The effects of QE II have just begun to impact mortgage rates (in this data) and we can only assume that the home price slide will accelerate.


ARCHITECTURE BILLINGS INDEX - http://www.aia.org/practicing/economics/AIAS076265
In my quest to add more indicators, my buddy Carrz suggested that we should use the Architecture Index.  Billings and Inquires are up based on their December survey.


MOODY'S / MIT TRANSACTION INDEX - http://web.mit.edu/cre/research/credl/rca.html
The Moody's / MIT Transaction Index recorded another rise of .6% for the month of November (released last week of Jan).  Commercial real estate has been very solid here and has not declined further.  Has the the bottom been made and are we in the clear?


MONSTER.COM INDEX -  http://about-monster.com/employment/index/15
While real estate prices may be going higher, job prospects seem to be not getting better.  In fact, the Monster.com job listing index has recorded another monthly decline.  Essentially Monster.com records the number of online job listings that are available.  This is the fourth straight drop in this data.  Are all the positions taken?  Monster tried to spin this and state that this is a 7% increase from the previous year's level, but I don't see it that way.  January of 2010 was the edge of the cliff, are we really expecting to be way over this level?


FOOD STAMPS - SNAP DATA - http://www.fns.usda.gov/pd/34SNAPmonthly.htm
Below is a graphic of the most recent food stamp data.  Almost 43.6 million, ok let's be exact 43,595,000 are obtaining food stamps at a cost of $5.8 billion!  Essentially each person is receiving $133 a month in government food assistance.


UCLA / CERIDIAN FUEL INDEX - http://www.ceridianindex.com/
January's release of the PCI shows a slight decline from December's big gains.  Ultimately this can probably be blamed on weather if you can believe it (and I actually do believe it for this stat!).


COPPOCK TURN INDICATOR


6 MONTH EURIBOR -
http://www.homefinance.nl/english/international-interest-rates/euribor-rates-6-months.asp
Interbank lending rates continue to climb.  We haven't heard much about Europe over the last couple of days, but we should keep Greece in mind and not be eased into any complacency.  It is coming, it is just a matter of when, rather than if.


US FINANCIAL CONDITIONS INDEX -
http://www.bloomberg.com/apps/quote?ticker=BFCIUS:IND
The US Financial Conditions Index not is solidly above zero which indicates that the economy is expanding.


BALTIC DRY GOODS INDEX -
http://www.bloomberg.com/apps/quote?ticker=BDIY&exch=IND&x=15&y=11
The Baltic Dry Goods Index continues its free fall.  Spot shipping rates are simply off the cliff and it is anyone's guess as to when the drop will abate.


USD - http://www.bloomberg.com/apps/quote?ticker=DXY:IND
The USD Index is captured below.  One might expect a defense of these levels here,. but one might expect alot of things in this economy that don't happen.  If we do see some strength in the dollar, we would expect to see the commodities complex sell off and perhaps the equity market too.  If we see more declines in the dollar index, we should see Garth and Ben out yelling "Party On Wayne!"


CORN -
Commodities like the softs (corn, wheat, etc) continue to rock.  Take a look at the graph for corn and note that we are right back at the levels of the summer of 2008 where President Bush happily signed the corn/ethanol subsidy bill and made life hard for Mexican families that choose to consume corn tortillas.  Isn't it great that we still subsidize corn based ethanol despite the fact that it is terribly wasteful and inefficient!  Wouldn't that corn be better placed in the stomachs of people rather than the fuel tanks of autos?


COMMODITIES SNAPSHOT -
Here is a neat snapshot of all of the commodities for the last 1 year period.  As Ben Bernanke testified today, there is no inflation, but they are watching the increase in commodity prices closely.  Hopefully they are watching those price levels rather than the same screens as the folks at the SEC. http://abcnews.go.com/GMA/sec-pornography-employees-spent-hours-surfing-porn-sites/story?id=10452544  (Remember this awesome revelation from April 2010?)


TRADING UPDATE
I want to wrap up and I'm forced to take a deep sigh.  We really have a mixed bag still where some portions of the economy look have begun their recovery and other parts are simply mired in a funk. 

Rail shipping looks to be improving or at least remaining at higher levels.
Commercial real estate seems poised to move higher.
Employment could go either way, but I'm leaning to the side of a slowing of hiring as opportunities are gone (filled or simply the job was removed).
Housing stinks and is essentially a lost asset at this point, especially with the specter of higher interest rates.
Commodities will soon hit the level where they inhibit any recovery in the global economy so I think there is limited upside.
Credit concerns have not abated and we are seeing discussions of haircuts in Greece and CDS blowing out to all time highs for Portugal.

With all of these negatives and a few positives it is just amazing to me to see many of the indices trading at or near July 2007 highs (and near almost all-time highs of Oct 2007).  I've struggled with how to characterize this economic and stock price move and I think the best way to capture it is to say that this has been a "RECOVERY IN ASSET PRICE ONLY".  In other words, the economy comeback we've seen is only in the levels of stock indices rather than in the basic fundamentals in the real economy.

Emerging markets continue to be of great concern for me thus today's FXI update and I still remain bullish on energy here as described in the 2011 outlook.  We have made it through January without the correction that I've been looking for, I don't know if it is merely delayed or just not coming.  My thesis that we'll see strength domestically through the first 4 or 5 months of the year still looks good but that is no reason to not remain vigilant.

GOATMUG


CHINA - LOVEABLE PANDA OR BLOOD SUCKING GRIZZLY BEAR (PART II)

Just a quick follow up on the China trade (FXI) I outlined last week. In the post titled, China - Great Big Loveable Panda or Blood Thirsty Bear I noted that the etf was close to breaking critical support at $42.00. As often is the case, I have been short that trade since the post and have slowly been bled to death by the daily POMO that makes markets go one direction despite the fundamentals that suggest the price action should be the opposite.


As of this writing at 9AM Eastern, FXI is trading at $41.79 pre-market. If we open here, this should be cause for a doubling of my short position, with a target on the downside of at least $39.00 and a lower target of $36.00
China raised one year interest rates yesterday by a quarter of a point to 6.06% as they attempt to cool off their overheating economy. Please see the following Bloomberg article on the topic - http://www.bloomberg.com/news/2011-02-09/hong-kong-gauge-drops-to-lowest-this-year-as-china-raises-rates.html
(FXI)

What does this mean for other emerging countries? The serious answer is I don't know. If we look at charts like EEM, I don't see anything there that is a big tell as to direction, although it is really just floating out in space and could easily drop back to support around $43.75. I think a better target might be found in a chart like the one below EWS (Singapore), it looks like a pretty good short with an easy stop above $14.00.
(EWS)


I will have the monthly macro update done this evening. Please continue to check in at http://www.goatmug.blogspot.com/ . Until then, be careful!


GOATMUG